
Advisors Shift Strategy: Box Spread Loans Gain Traction as Fed Hawks Keep Borrowing Costs High
As the Federal Reserve maintains a hawkish stance and interest rates remain stubbornly elevated, financial advisors are increasingly advising clients to move away from traditional, variable-rate borrowing vehicles. With mortgage lock-in effects keeping many homeowners tethered to ultra-low rates from years past, and the cost of capital rising for newer credit lines, a sophisticated alternative is emerging: the box spread loan. This options-based strategy, which allows investors to borrow against their portfolios at fixed rates that are insulated from central bank volatility, is rapidly becoming a preferred tool for those seeking liquidity in a challenging economic climate.
The shift is largely driven by a squeeze on traditional liquidity sources. The Federal Open Market Committee, in a move that signaled continued caution, voted 10-2 on October 28, 2026, to hold the federal funds rate in a range of 3.75% to 4%. While the majority opted for stability, the dissent of Governor Lisa Cook and Cleveland Fed President Beth Hammack—both of whom favored a quarter-point hike—underscored the persistent pressure on the Fed to combat inflationary forces. This decision followed a September 2026 rate increase, the first such move in three years, signaling the end of the era of near-zero borrowing costs.
The implications for personal finance are significant. Data from Realtor.com, drawing on analysis of Federal Housing Finance Agency information, reveals that 49.1% of outstanding U.S. mortgages carried interest rates below 4% in the second quarter of 2026. Conversely, new 30-year mortgage rates have consistently hovered above 7%. For the vast majority of these homeowners, a cash-out refinance is a non-starter, as it would destroy the value of their existing low-interest debt. Consequently, many have turned to Home Equity Lines of Credit (HELOCs) or margin loans to bridge liquidity gaps. However, as these instruments are predominantly variable-rate, their costs have surged alongside the Fed’s policy shifts, leaving borrowers exposed to the risk of rising monthly payments.
In this environment, the box spread loan has gained prominence as a more predictable alternative. A box spread is a four-leg options position, typically constructed using S&P 500 index options, that establishes a fixed future obligation. By entering into this position, a client can secure cash today in exchange for a set repayment at expiration. Because the implied rate of these loans tracks Treasury yields rather than the fluctuating credit spreads often associated with retail lenders, they offer a degree of stability that standard margin loans cannot match. Furthermore, because these contracts fall under Section 1256 of the tax code, borrowing costs are deductible as capital losses, characterized as 60% long-term and 40% short-term, regardless of how the funds are deployed.
Why Box Spread Loans Appeal as Rates Rise
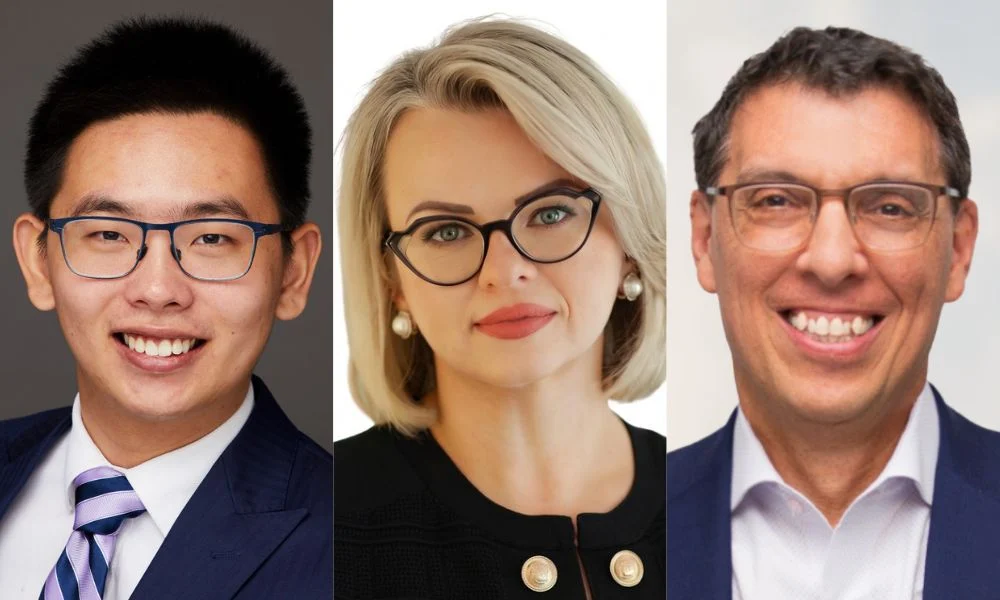
For Joseph Wang, co-founder of the San Francisco-based firm SyntheticFi, which specializes in structuring box spread financing for financial advisors, the decision to borrow should never be viewed in isolation. Instead, he emphasizes the importance of the "total cost of funds." This includes not only the explicit interest rate but also the forgone investment growth, tax implications, and the client’s inherent tolerance for risk.
"The right question is the total cost," Wang says. He notes that selling off high-performing assets to generate cash often triggers an immediate and substantial tax bill, while simultaneously cutting the investor off from future market appreciation. In his assessment, traditional HELOCs are simply too expensive and suffer from the fatal flaw of being tied exclusively to floating interest rates, making them ill-suited for the current environment.
"Margin loans are better than HELOCs, but since they are always floating, they are not suitable for home financing under the current rate environment," Wang explains. "The best option is a box spread. They are cheap, often tracking at Treasury yields plus 0.3%, and they can be structured with a fixed or floating rate or even an amortization schedule. Plus, box spreads are tax-efficient because the cost of financing is treated as capital losses, a unique advantage over other options."
Total Cost of Funds Drives the Borrowing Decision
The strategic deployment of leverage requires a meticulous examination of a client’s entire financial picture. Rick Simonetti, founding partner, CEO, and head of wealth planning at Fidelis Capital, approaches the issue from a "cash-first" philosophy. For Simonetti, leverage is only part of the conversation when a client’s liquidity needs exceed their available cash. Once that threshold is crossed, the analysis shifts to after-tax outcomes. The central question becomes: is the tax hit from liquidating appreciated assets or tapping into retirement accounts greater than the after-tax cost of a structured loan?
"With limitations on the deductibility of mortgage and investment interest and the recent uptick in rates, those traditional lending sources—HELOCs, traditional mortgages, margin, and even traditional secured lines—become less appealing," Simonetti observes. He points out that for investors with significant holdings, there are solutions that provide an outcome resembling leverage while keeping the after-tax cost of funds near the market’s risk-free rate.
"As an example, that after-tax cost of funds for a 3-year term today is around 4% to 4.5%," Simonetti says. "With this as a fixed rate, the appeal in today’s interest rate environment is clear."
Should Clients Lock in a Fixed Rate or Wait?
Navigating the current rate environment requires a tailored approach. Anna M. Blokh, managing director and senior lending officer at OpenArc Corporate Advisory, evaluates each recommendation based on a four-factor framework: the intended purpose of the capital, the anticipated duration of the balance, the risk profile of the underlying collateral, and the client’s specific exposure to interest rate fluctuations.
"If a client values payment certainty and expects to carry the balance for an extended period, locking in a fixed rate can make sense," Blokh explains. "This approach provides greater predictability in cash flow and borrowing costs. If a client prefers to wait for rates to decline, we discuss whether the potential savings from lower rates outweigh the value of certainty today, while staying closely connected as the interest-rate environment changes."
This leads to a broader debate about the hazards of market timing. Wang is particularly wary of clients attempting to outmaneuver the Fed. "Treasury rates, or rates in general, are a highly efficient market," he notes. "Clients don’t have the extra information as an advantage to ‘play the rates.’ You can spend all night parsing FOMC transcripts, but that doesn’t mean you’ll predict where rates go next."
For Wang, the structure of the loan should match the purpose of the capital. He suggests that a floating-rate structure might be appropriate for a bridge loan that a client intends to pay off within six to 12 months. Conversely, for a primary residence or long-term debt, a fixed-rate box spread or a laddered approach is far more prudent.
Refinancing Expensive Debt — and the Risks
For many clients, the immediate need is not new capital, but rather the restructuring of existing, high-cost debt. Blokh emphasizes that before making any changes, it is essential to conduct a rigorous break-even analysis. This process involves reviewing existing terms, identifying any potential refinancing penalties, and carefully calculating the tax implications.
"We also conduct a break-even analysis and evaluate whether the proposed loan could introduce risks that outweigh the potential interest savings," Blokh says. "Ultimately, any refinancing strategy should align with the client’s broader financial goals and risk profile."
The benefits of utilizing liquid securities as collateral—as is the case with box spreads—rather than real estate or business cash flow, can result in borrowing costs that are 3 to 6 percentage points cheaper than conventional alternatives. However, this structure is not without its perils. Like a standard margin loan or a securities-based line of credit, a box spread requires ongoing maintenance of the collateral. A significant, sustained market downturn could trigger a margin call, forcing the investor to either deposit more cash or liquidate holdings at an inopportune time.
"The main criteria is the liquid asset level," Wang says, noting that while the maximum borrowing capacity is typically around 50% of the portfolio, many of his clients prefer to keep their exposure below 30% to build in a buffer against volatility. "At the end of the day, if a client has the assets, why pay more?"
Ultimately, while the box spread has become a compelling tool for the modern advisor, it is not a universal solution. Simonetti notes that many clients are simply unaware of these alternatives, but he cautions that lower cost does not always equate to a better fit.
"When we take a look at a balance sheet, we must review the liability side and assess whether the current structure is the best structure," Simonetti says. "We have, in many cases, found a solution to lower the after-tax cost of funds and pay off debt or leverage with a higher after-tax cost of funds. In others, say a mortgage from years ago with a 3% rate, the client is better off retaining the current solution."
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |