American Airlines Cuts Full-Year Outlook as Surging Fuel Costs Offset Record Revenue
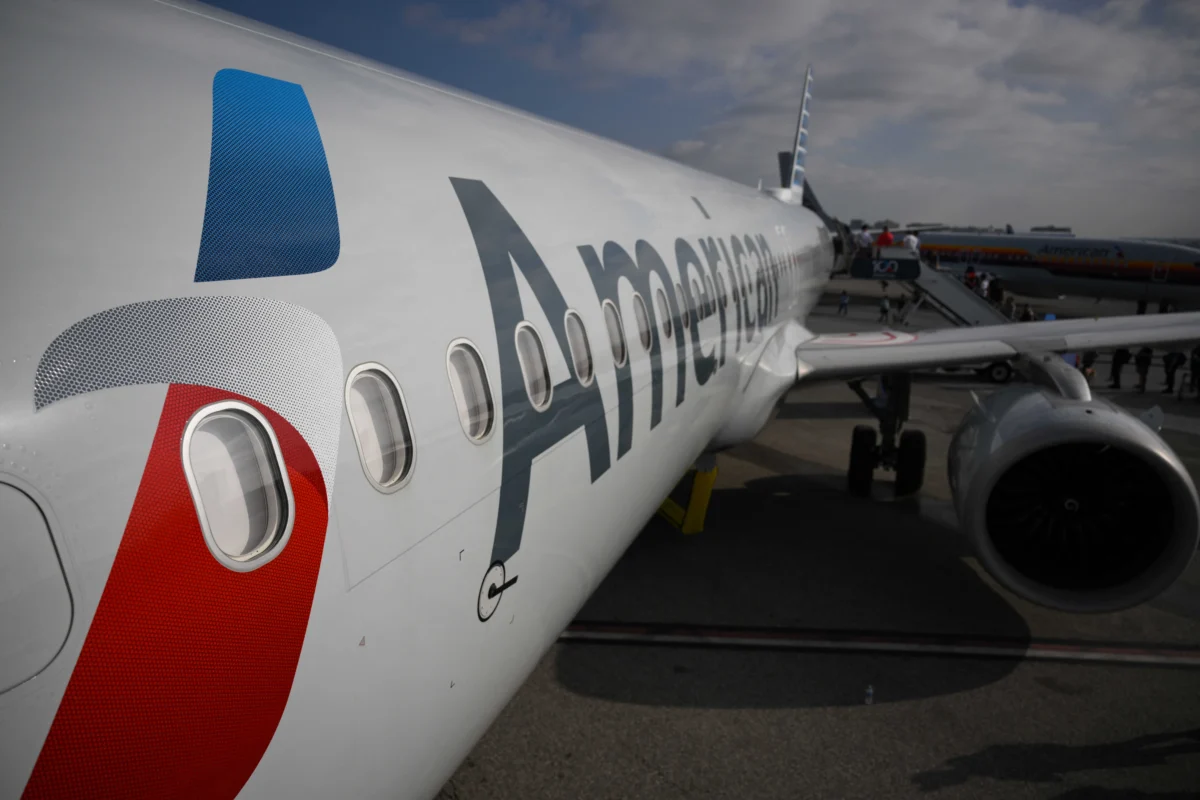
American Airlines has slashed its financial forecast for the year, warning investors that it now expects deeper losses as a sharp spike in jet fuel prices completely eclipses record-shattering passenger revenue. The Fort Worth, Texas-based carrier announced Thursday that it is slowing its capacity growth for the upcoming year in response to the volatile macroeconomic and geopolitical pressures reshaping the aviation industry.
The airline now expects to post an adjusted net loss of between $1 and $1.60 per share for the full year. This marks a notable and painful downward revision from guidance issued just a few months prior in July, when the carrier projected its adjusted full-year earnings per share would range between a loss of 65 cents and a modest profit of 65 cents.
The struggle to remain profitable despite robust consumer demand highlights the acute vulnerability of traditional network carriers to commodity market shocks. American is now the fourth major U.S. commercial carrier to significantly cut its financial outlook for the year, joining industry peers as they grapple with surging jet fuel costs triggered by the onset of the Iran war.
According to comprehensive airline reports and federal economic data, the relentless climb in jet fuel prices has driven airfares up by more than 20% compared to the same period last year. The ripple effects have been felt across the entire domestic aviation sector. Major competitors, including Delta Air Lines, United Airlines, and Southwest Airlines, were forced to slash their respective financial outlooks earlier this month as operating expenses ballooned.
For commercial airlines, jet fuel consistently ranks as the single largest operational expense second only to labor costs. The sudden and severe spike in fuel prices has effectively added billions of dollars in unexpected expenses to carrier balance sheets over the course of the year. For American Airlines alone, the financial impact was starkly visible in the third-quarter ledger, where the total fuel bill skyrocketed by 67.5% compared to the previous year, reaching an imposing $4.64 billion.
Despite the heavy financial headwinds, airline executives emphasized that the carrier’s underlying operational momentum and customer demand remain exceptionally strong.
"American delivered record third-quarter revenue and the strongest year-over-year revenue growth in my career, with premium performance leading the way," said American Airlines CEO Robert Isom in an official news release detailing the quarterly financial performance.
Confidence in 2027 Profitability

Even as the airline lowered its expectations and braced for deeper losses, CEO Robert Isom sought to reassure Wall Street during an earnings call with analysts and investors on Thursday. Isom expressed "great confidence" that the company is on a firm trajectory to successfully return to profitability next year.
Isom has faced mounting pressure from shareholders and industry analysts to boost financial returns at the carrier. For quarters, American Airlines has noticeably trailed its primary legacy rivals, Delta and United, both of which have managed to navigate the turbulent economic landscape with stronger profit margins. In an effort to close this competitive gap, American has poured substantial capital into modernizing its passenger experience. The airline has been actively investing in the construction of new airport lounges and the rollout of revamped aircraft cabins featuring a higher concentration of premium seats. Furthermore, the carrier reversed a previous strategic decision earlier this year, announcing plans to reintroduce popular seat-back entertainment screens to its narrow-body fleet.
The push for financial and operational improvement has also triggered a comprehensive management shake-up across the organization. Earlier this month, the airline appointed a new network chief, marking the latest in a series of high-level personnel changes designed to streamline operations and commercial strategy. These moves followed key leadership appointments within the operations department and commercial team. Notably, American brought in industry veteran Nat Pieper last year to serve as its new commercial chief, tasked with optimizing revenue streams and corporate partnerships.
Robust Demand and Strategic Fleet Decisions
Underpinning executive optimism is the continued strength in international and premium-travel demand, which has shown virtually no signs of cooling off despite broader economic uncertainties and higher ticket prices. Capitalizing on this strength, American announced in late September that it would significantly deepen its commercial partnership with Alaska Airlines. Under the expanded agreement, the Seattle-based carrier is set to formally join American’s lucrative trans-Atlantic and trans-Pacific joint businesses, a move designed to enhance global connectivity and capture a larger share of high-yield international travelers.
At the same time, airline executives revealed that American is rapidly closing in on a major acquisition deal for new wide-body aircraft to modernize and expand its long-haul fleet. Chief Financial Officer Devon May told CNBC in an interview on Thursday that the carrier has thoroughly evaluated several advanced aircraft models for the prospective order, specifically considering the Boeing 787 Dreamliner, the Airbus A330, and the Airbus A350.
Looking ahead to the final quarter of the year, American Airlines provided its financial projections for the upcoming period. The carrier forecasts an adjusted loss ranging between 50 cents and $1.10 per share for the fourth quarter. Total operating revenue for the period is projected to climb by as much as 22.5% compared to the same period a year earlier, while system capacity is expected to expand by 5.5% to 6.5%.
The financial results reported for the third quarter illustrated the severe pinch of rising operational costs against a backdrop of growing top-line sales. For the three-month period ending September 30, American reported a net loss of $269 million, or 41 cents per share. This compares unfavorably to a net loss of $114 million, or 17 cents per share, recorded during the corresponding period a year earlier. When adjusting for one-time, non-recurring items, the airline reported an adjusted loss of 28 cents per share, which aligned closely with the consensus expectations of Wall Street analysts.
Total operating revenue for the third quarter saw a robust double-digit increase, jumping 19.3% from a year earlier to reach $16.34 billion, successfully matching expectations compiled by LSEG. However, the impressive top-line growth was entirely neutralized by the surging cost of fuel, leaving management focused on executing its turnaround strategy and steering the airline back toward sustained profitability in the years ahead.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |