
Global Venture Capital Rebounds Strongly in 2026 as Artificial Intelligence Megadeals Drive Record Funding
Global venture capital funding is mounting a significant rebound this year, propelled forward by historic, multibillion-dollar investments flowing into artificial intelligence startups. While transaction counts have retreated to historic lows, the sheer capital deployed into a select group of market-leading companies has pushed equity financing to heights not seen in years, reshaping the global technology investment landscape.
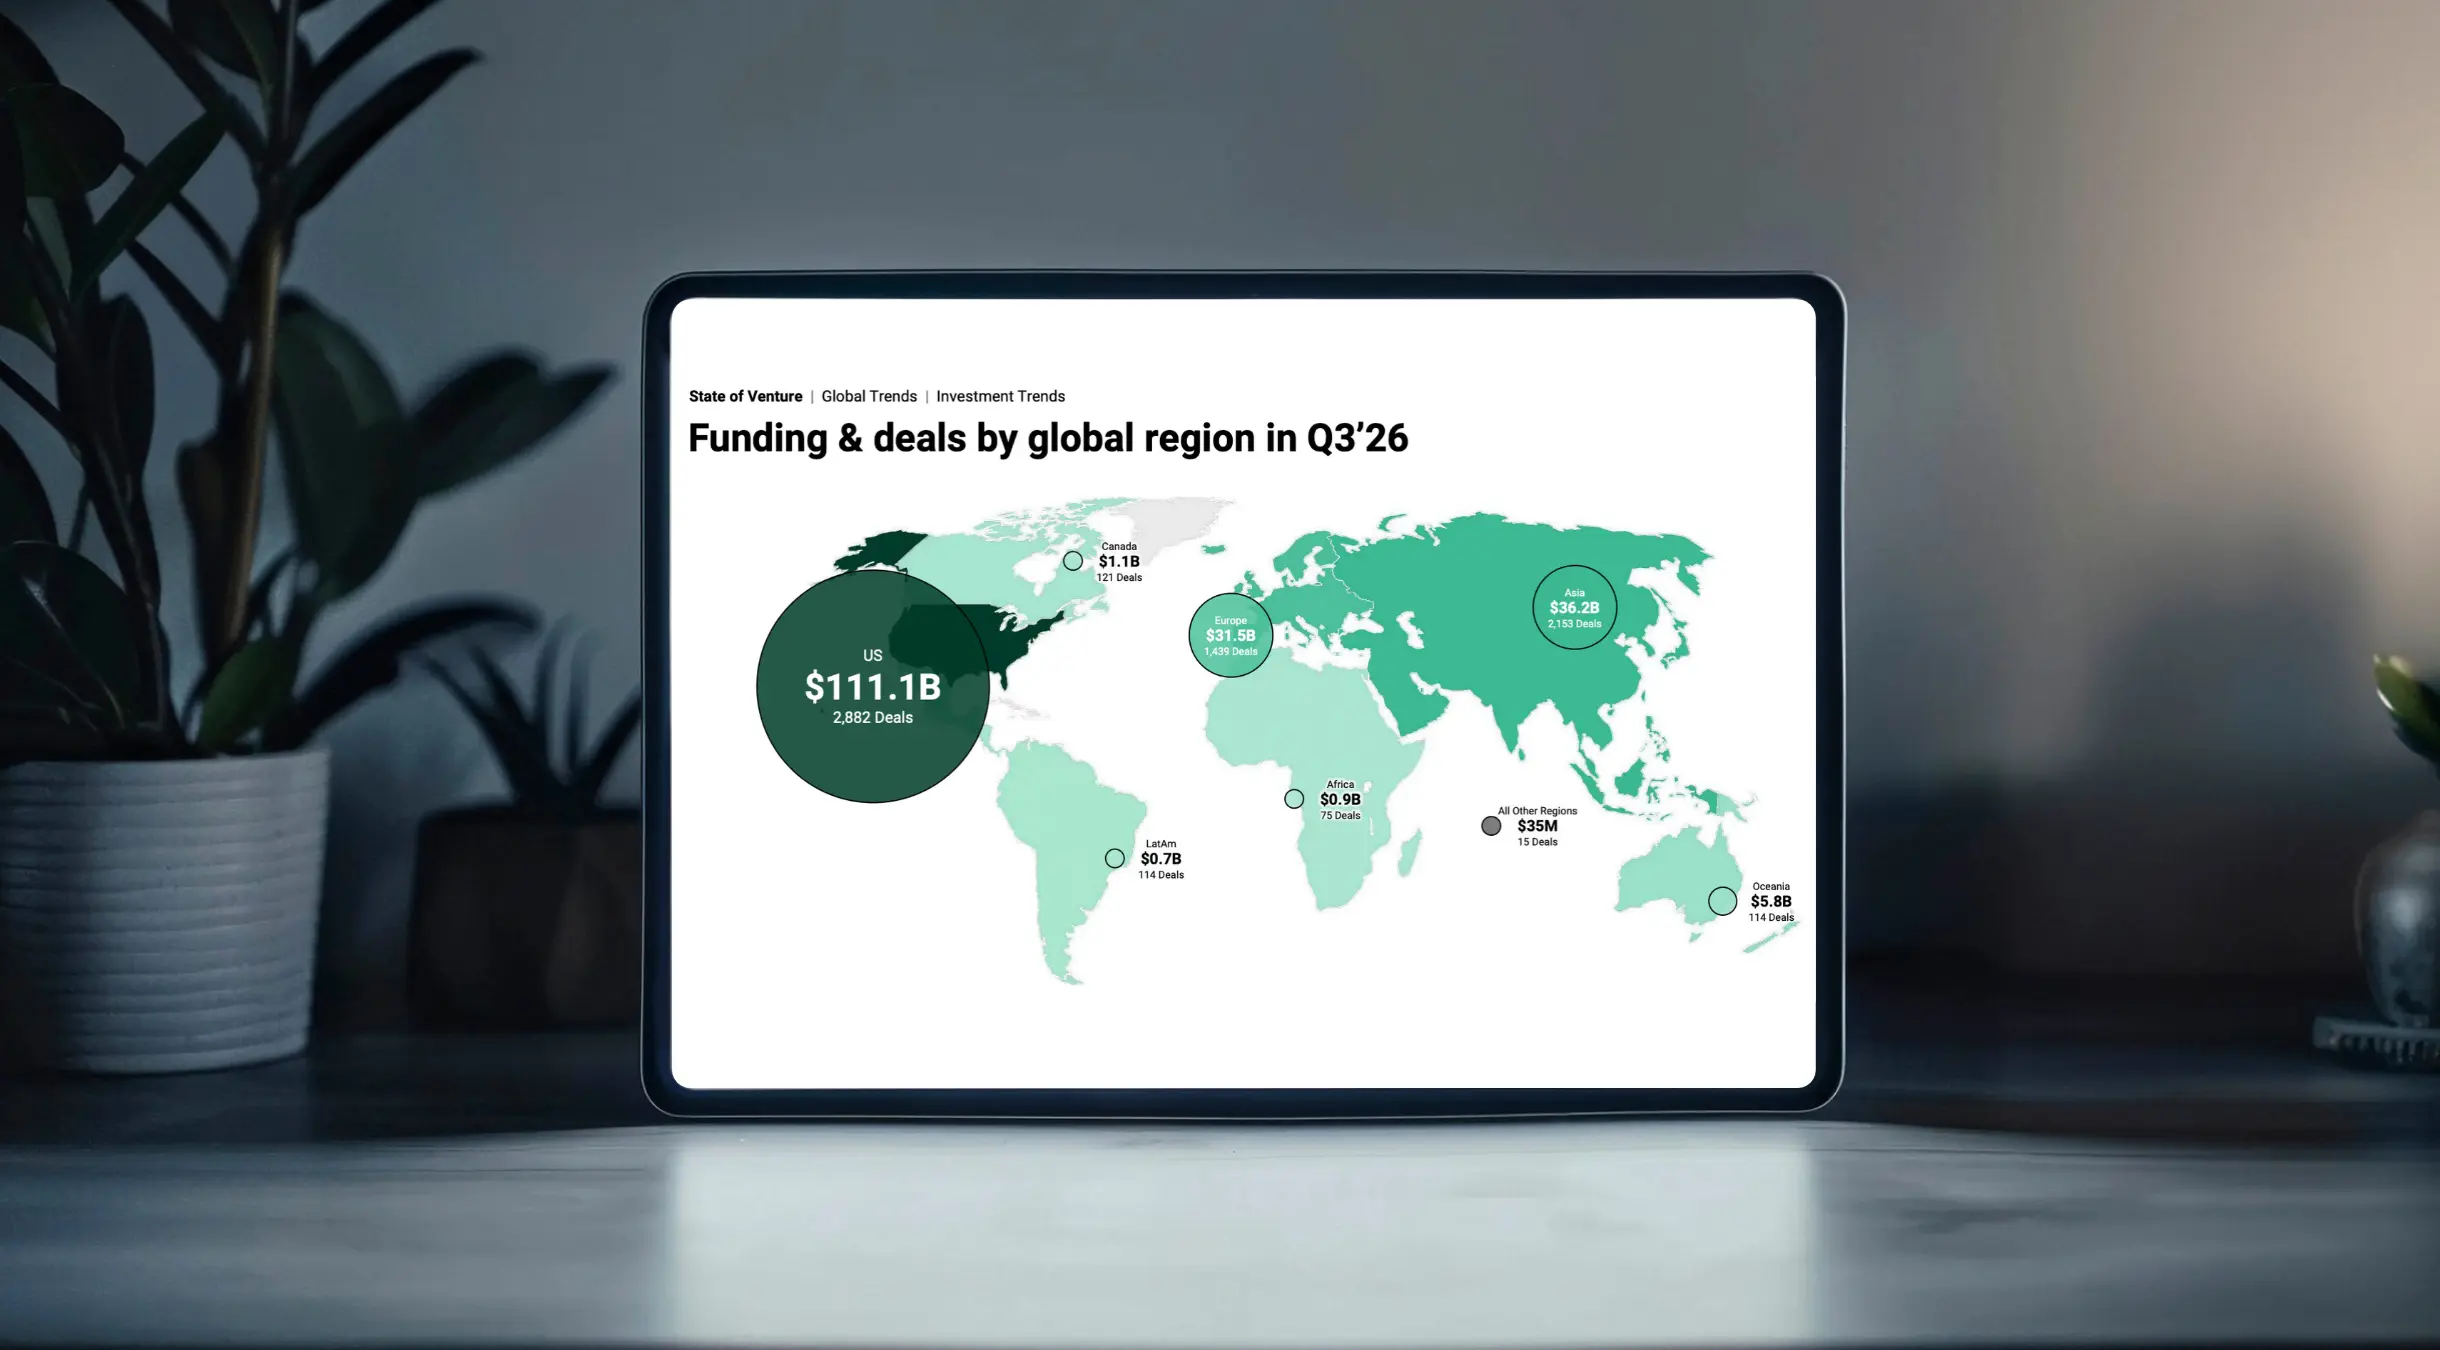
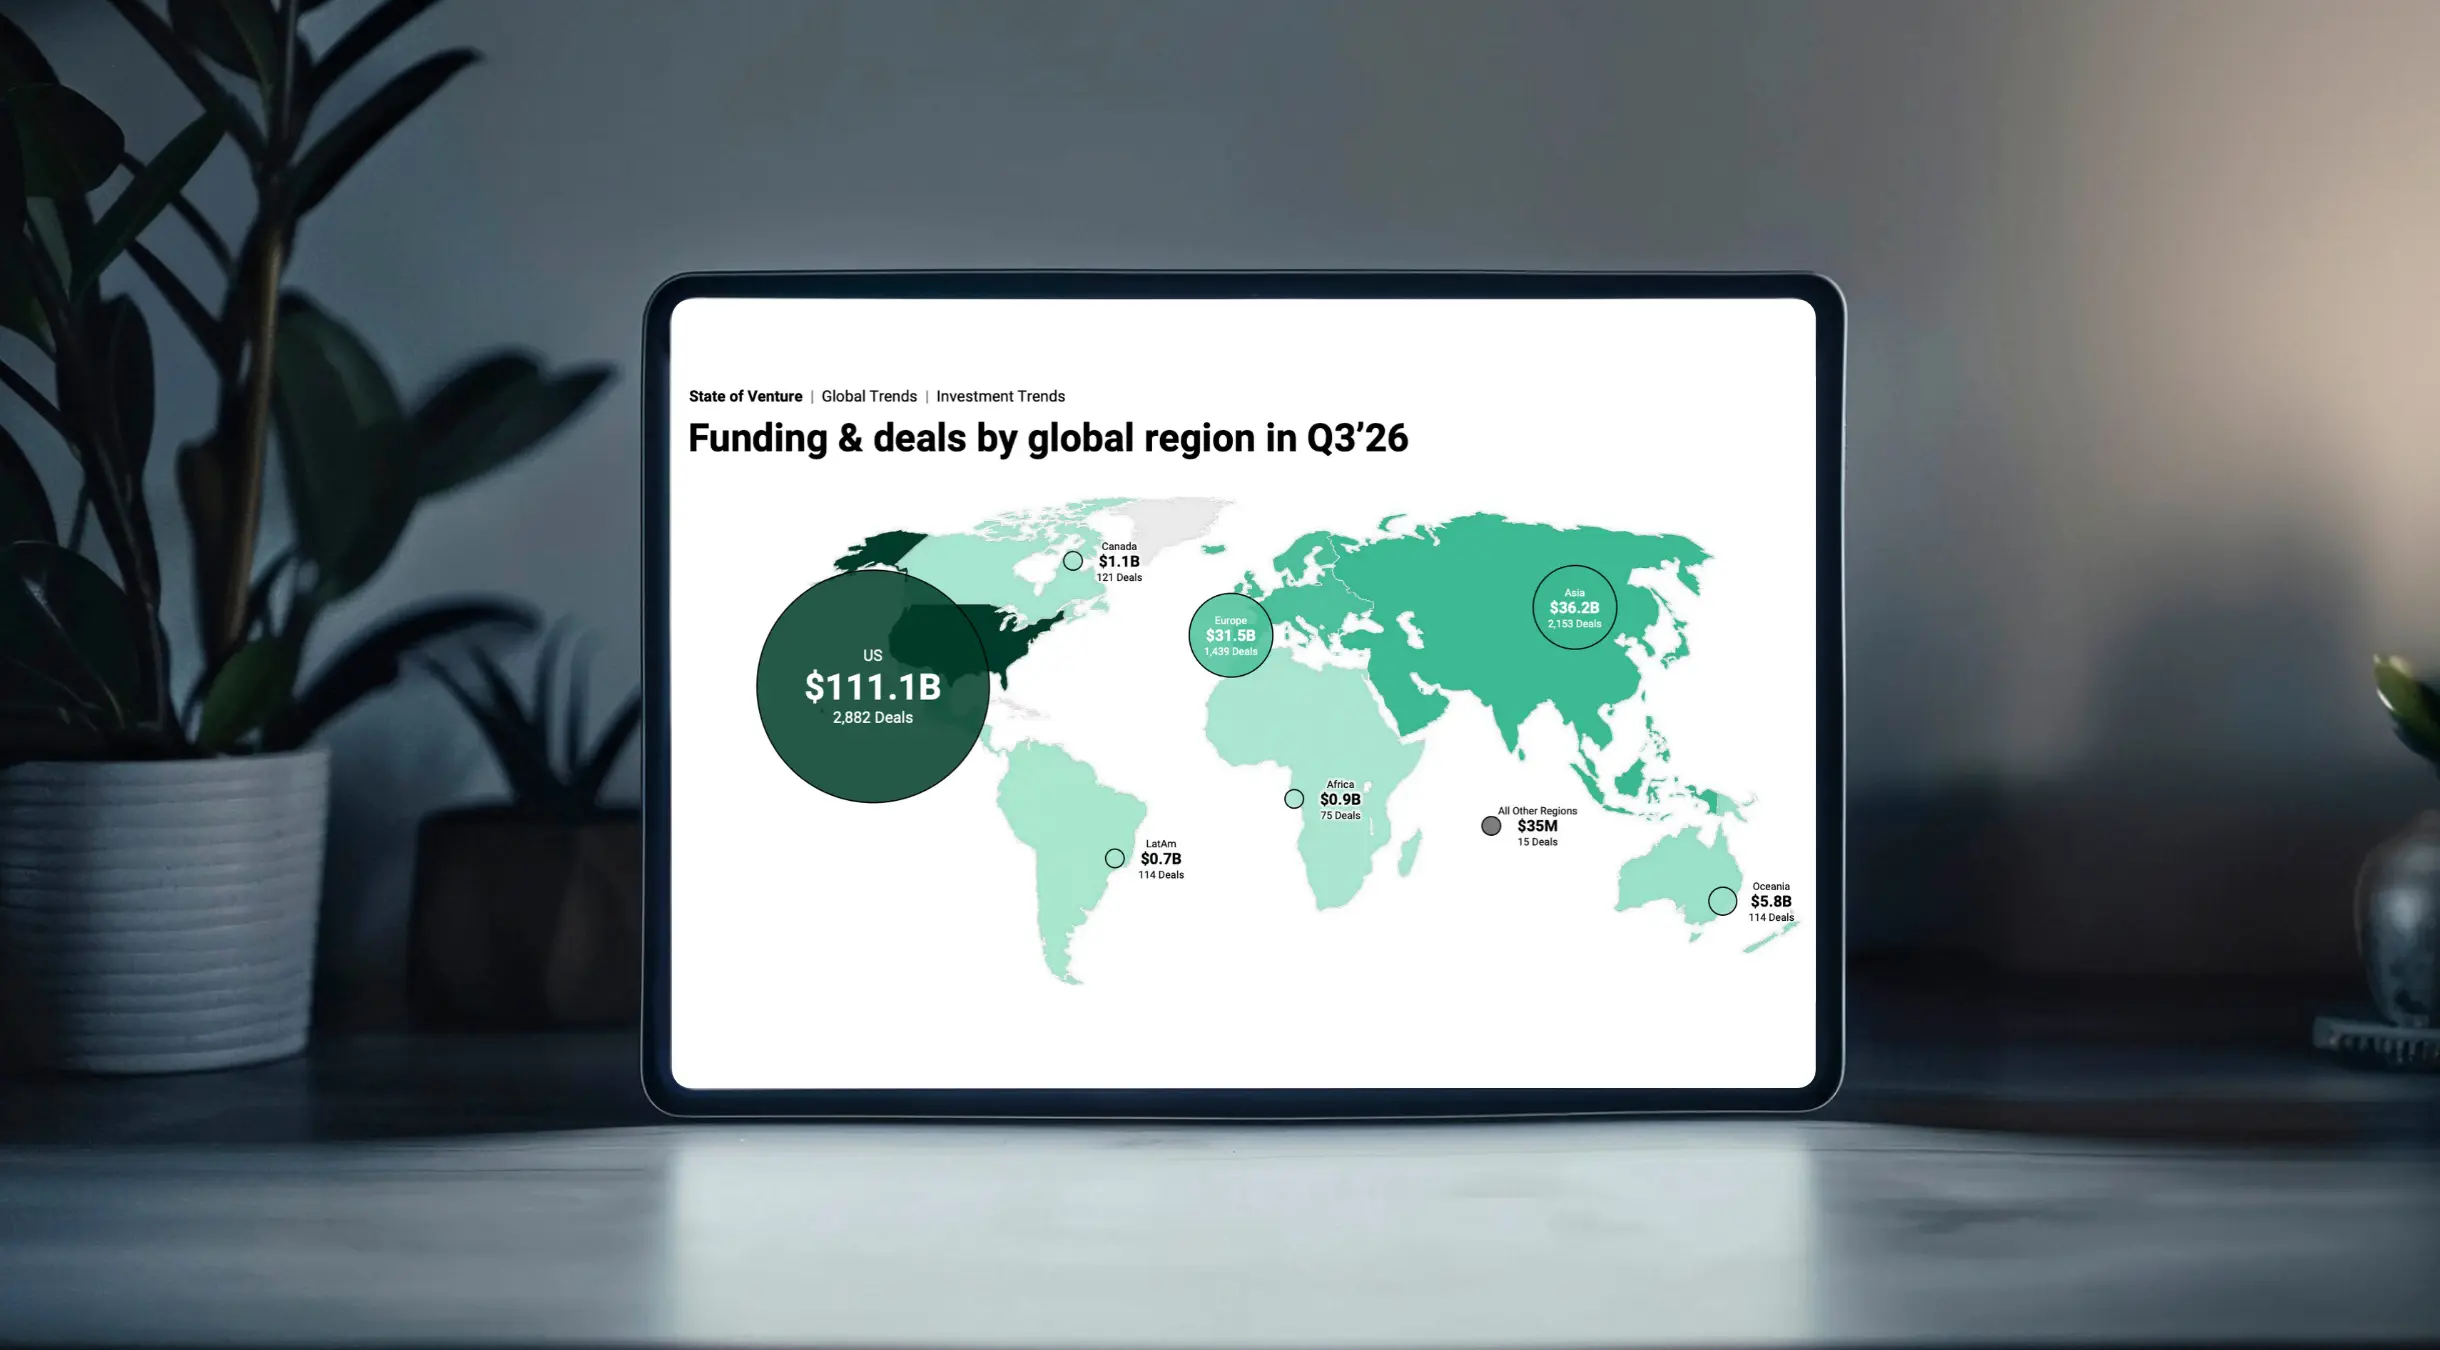
According to new comprehensive data released by CB Insights in its State of Venture Q3 2026 report, worldwide venture capital funding reached US$187.2 billion in the third quarter alone. This performance pushed the year-to-date total to an impressive US$698.3 billion. When measured against the same nine-month period in 2025, the latest figures represent a remarkable 108.9% increase, setting a record-high trajectory for the entire calendar year.
This unprecedented capital influx has occurred against a backdrop of declining deal activity. Transaction volumes continued to slide through the third quarter of 2026, dropping 23% quarter-over-quarter to settle at 6,913 transactions globally. This contraction marks a record low for deal count, illustrating a bifurcated market where investors are writing vastly larger checks for a much smaller, highly concentrated portfolio of mature technology companies.
The global surge in equity funding is overwhelmingly driven by massive capital rounds directed toward foundational artificial intelligence developers. OpenAI, the creator of ChatGPT, has captured headlines throughout 2026 with historic fundraising efforts. The company raised a staggering US$132 billion over the course of the year so far, comprising a massive US$122 billion funding round finalized in March 2026, followed by an additional US$10 billion investment from SoftBank Group in October.
Similarly, Anthropic, the San Francisco-based developer of the Claude AI assistant, secured US$95 billion in equity financing through two substantial tranches: a US$30 billion round in February 2026 and an even larger US$65 billion financing round in May. Together, the combined fundraising totals of just these two AI giants account for approximately one-third of all global venture capital funding deployed throughout the year.
Corporate strategy behind these capital raises varies, though both companies are heavily utilizing funds to scale physical infrastructure and secure future market dominance. OpenAI intends to channel its proceeds into financing its substantial, long-term infrastructure commitments. Furthermore, the capital serves to heavily bolster its balance sheet as potential turbulence in public equity markets threatens to further delay its anticipated initial public offering, which has been targeted for 2027.
Market intelligence indicates that OpenAI’s financial performance continues to expand rapidly alongside its capital requirements. Sources familiar with the matter revealed that the company’s annualized revenue has climbed to US$50 billion, with projections indicating it could reach US$70 billion by the close of 2026. Reports suggest the AI pioneer is already engaged in discussions to secure an additional US$30 billion in funding at a valuation exceeding US$1.4 trillion, with participation anticipated from major institutional backers such as SoftBank and Abu Dhabi-based MGX.
Anthropic is deploying its capital to advance sophisticated safety and interpretability research, expand its underlying computational infrastructure to meet surging enterprise demand for the Claude ecosystem, and scale its commercial product offerings and strategic enterprise partnerships.
Financial disclosures underscore the robust commercial traction underpinning Anthropic’s growth. The company reported a third-quarter revenue of US$16.8 billion ahead of its planned initial public offering slated for November. Significantly, Anthropic has demonstrated positive cash flow generation, taking in US$1.70 in revenue for every dollar spent on computing power during the third quarter. Wall Street analysts and institutional investors anticipate that Anthropic’s annualized revenue run-rate will reach US$110 billion by the end of the year.
Across the broader technology landscape, artificial intelligence startups have absorbed US$495.5 billion across the first three quarters of 2026. This massive aggregation of capital gives the AI sector a commanding 71% share of all global venture capital funding recorded year-to-date.
Global VC Funding Trends
The dominance of AI and mega-rounds has profoundly distorted average transaction sizes across the broader venture ecosystem. The global average deal size more than doubled over the past year, surging from US$23 million in 2025 to US$49.8 million through the first three quarters of 2026.
This inflationary trend in round sizes is far more acute within the artificial intelligence vertical. AI-focused funding rounds are averaging US$91.3 million year-to-date in 2026, representing an 188% increase compared to an average of US$31.7 million throughout the entirety of 2025.
Mega-rounds—defined as equity financing events valued at US$100 million or more—accounted for approximately 80% of total global funding in the third quarter of 2026, capturing US$149.2 billion. This capital concentration occurred despite mega-rounds representing a tiny fraction of total transaction volume, accounting for only 299 out of the 6,913 total deals completed during the quarter. This marks the third consecutive quarter that mega-rounds have commanded roughly 80% or more of overall quarterly venture deployment.
Regional funding distribution shows continued dynamism across major international markets. Asia maintained its position as the second-largest recipient of global venture capital activity, capturing 31% of worldwide deployment in the third quarter of 2026 with US$36.2 billion distributed across 2,153 deals. Cumulatively, Asian enterprises have secured US$99.8 billion year-to-date, marking a four-year high and a 130% year-over-year increase.
Singapore experienced a particularly pronounced surge in investment activity. The city-state’s startups raised US$6.7 billion across 72 transactions in the third quarter of 2026 alone, lifting the country’s year-to-date total to US$14.4 billion. This figure represents an all-time annual peak for Singapore and a dramatic 220% jump compared to the same period in the previous year.
Meanwhile, European technology startups secured US$31.5 billion in the third quarter of 2026, representing a 13% quarter-over-quarter increase and marking the region’s strongest quarterly funding total since the second quarter of 2022. This performance elevates total European venture funding for the year to US$82 billion.
The largest individual equity deals in Europe during the third quarter were concentrated in France and the United Kingdom, alongside a major sports and infrastructure transaction. Mistral AI, a prominent French artificial intelligence company specializing in frontier large language models, secured a US$3.5 billion financing round to advance its sovereign open-weight models. Nscale, a London-based vertically integrated AI infrastructure and cloud computing provider, raised US$2.4 billion ahead of its own planned public market debut. Additionally, professional football club Liverpool FC completed a substantial US$2.2 billion transaction involving high-profile international investors.
Beyond the dominant artificial intelligence sector, traditional technology verticals maintained steady, albeit smaller, shares of total market activity. Financial technology, or fintech, remained a prominent vertical, attracting US$11.8 billion in venture capital funding during the third quarter of 2026 and capturing 6.3% of global investment. Digital health also maintained a notable market presence, securing US$8.3 billion to account for 4.4% of total third-quarter venture funding.
As the venture ecosystem enters the final quarter of the year, industry leaders and market forecasters anticipate sustained momentum in global investment, with capital continuing to concentrate heavily within the broader artificial intelligence value chain.
Research from KPMG indicates that forward-looking investment is likely to accelerate further within specialized infrastructure layers, physical AI, industrial automation, and advanced robotics. Furthermore, this expansive capital momentum is projected to spill over into adjacent sectors, most notably defense technology—as national governments increasingly prioritize autonomous, AI-enabled defense systems and domestic technological sovereignty—alongside continued private investment in alternative energy infrastructure.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |