
Jim Cramer Says Aerospace Sell-Off Creates Long-Term Buying Opportunities for GE and Boeing
The recent, sharp sell-off across aerospace stocks may be forging compelling entry points for investors willing to look past the industry’s near-term operational challenges and macroeconomic headwinds, according to CNBC’s Jim Cramer.
For months, the aerospace sector has found itself under intense pressure. Rising global oil prices and elevated interest rates have combined to raise widespread concerns regarding the long-term demand for new commercial aircraft. Surging fuel costs directly squeeze airline profit margins, potentially forcing commercial carriers to trim unprofitable routes and scale back their ambitious aircraft purchase plans. Simultaneously, higher interest rates make the financing of brand-new planes significantly more expensive, compounding the prevailing demand worries that have weighed heavily on investor sentiment.
Even with a modest gain of more than 3% on Tuesday, GE Aerospace shares remain down roughly 23% from their 52-week high of nearly $389 per share, which was reached back on August 6. The stock is currently down about 3% for the year to date. Meanwhile, a steep slide of more than 10% for Boeing on Tuesday dragged the CNBC Investing Club stock down roughly 23% for 2026. For broader market comparison, the iShares U.S. Aerospace & Defense ETF (ITA) is trading down about 4% year to date, while the broader market S&P 500 index has climbed over 12.5% over the same period.
Despite this turbulent backdrop, the "Mad Money" host remains optimistic about the sector’s trajectory. Speaking to investors, Cramer urged a broader perspective on the industrial group. If investors are willing to adopt a long-term horizon, he believes the sector will ultimately emerge as a secular, long-term market winner. The overarching narrative that higher fuel prices and elevated interest rates will permanently crush demand simply appears to be flat-out wrong.
GE Aerospace Delivers Strong Third Quarter Despite Cash Flow Dip

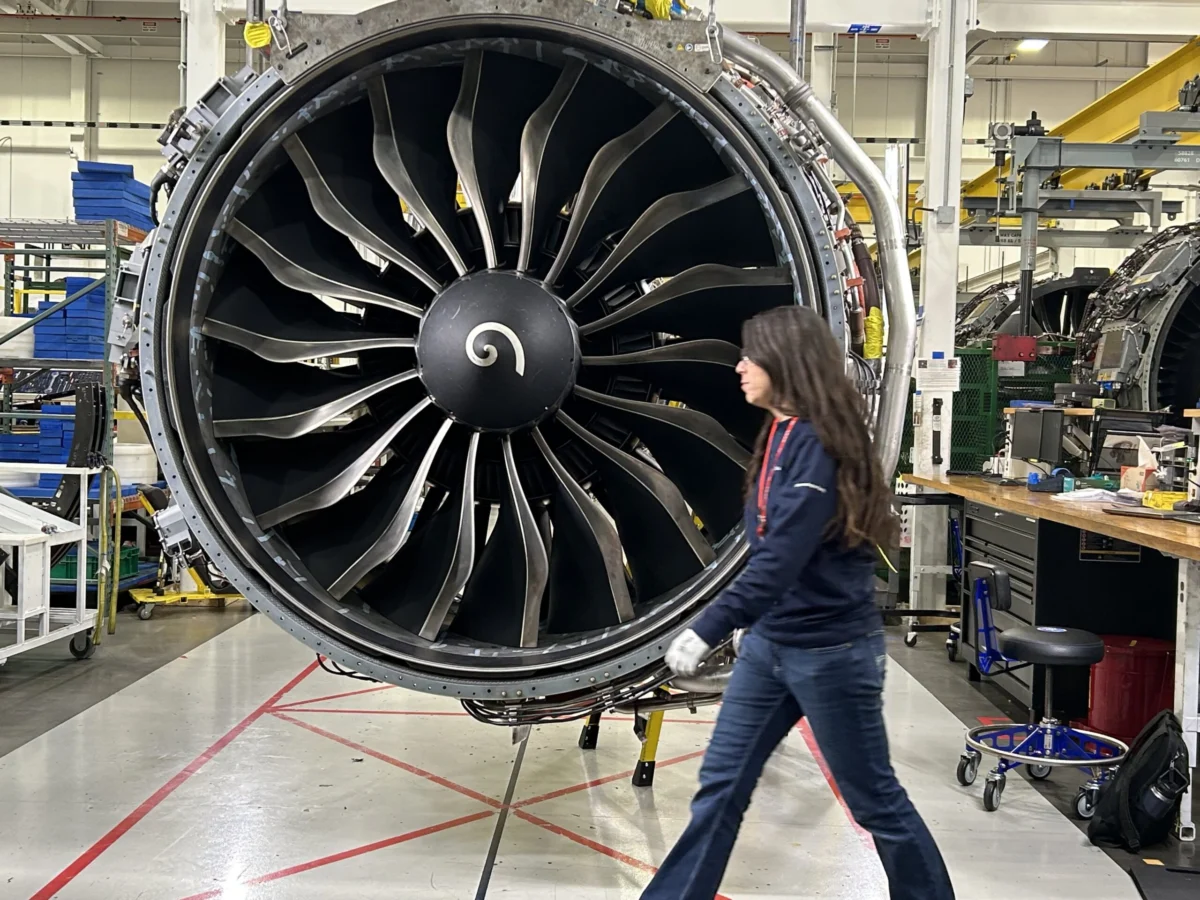
GE Aerospace delivered a robust third quarter report last week, yet the market reaction reflected the cautious mood surrounding the broader industry, leaving the stock unable to catch a lasting break. Cramer views the resulting market weakness as a prime buying opportunity, pointing specifically to the exceptional, ongoing demand for the company’s advanced jet engines.
During the quarter, orders within GE’s commercial aerospace business surged by an impressive 58%. This growth was propelled by an extraordinary 235% increase in equipment orders alone, which ultimately swelled the company’s total order backlog to a staggering $170 billion.
Addressing the core macroeconomic anxieties that have punished the sector, Cramer noted that the primary concern for aerospace investors over the past couple of months has been the persistent fear that rising oil and borrowing costs would dry up plane orders, leading directly to a drought in jet engine orders for GE. However, he emphasized that the incredible order numbers delivered by GE—particularly on the commercial side and specifically for new equipment—demonstrate that this catastrophic scenario is clearly not playing out in reality.
The third-quarter report was not entirely without its shortcomings, however. Free cash flow experienced a 14% decline compared to the same period a year ago, coming in slightly below Wall Street expectations. Furthermore, GE’s valuation remains elevated, trading at roughly 37 times the midpoint of its updated full-year earnings guidance.
When a company carries such a lofty valuation multiple, the quarterly report needs to be a clean beat-and-raise event to satisfy the market, and unfortunately, investors did not get that scenario this time around. Even so, Cramer asserted that the underlying strength of GE’s core business far outweighs these temporary, headline-driven concerns. From his perspective, GE looks fine to buy right now.
Boeing Faces a Tougher Road Amid a Multiyear Free Cash Flow Reset

While Cramer expressed considerable confidence in GE Aerospace, his outlook on Boeing carried a notably more cautious tone.
Boeing reported a generally mixed third quarter, and while free cash flow managed to beat consensus analyst estimates—representing a critical metric to watch closely in any ongoing Boeing turnaround effort—it was the commentary delivered during the accompanying earnings call that truly rattled investors and sent the stock tumbling to new 52-week lows.
During the call, management outlined a multiyear outlook on free cash flow that fell noticeably short of Wall Street expectations. This conservative projection was driven in part by heavy upfront capital spending tied to a major new contract to develop next-generation fighter jets for the U.S. Navy. Additionally, company executives informed analysts and shareholders that Boeing would not significantly accelerate or ramp up its 737 Max production rates until late next year, further delaying the expected financial recovery.
Cramer expressed hope that this painful guidance reset could ultimately serve as a constructive clearing event for the stock. While he acknowledged that some impatient investors will likely throw in the towel and sell their shares, everyone who remains invested moving forward will be operating with a new, much more realistic set of free cash flow targets.
Despite the near-term pain and operational hurdles, Cramer was quick to highlight Boeing’s massive, enduring order backlog as definitive proof that underlying demand for its commercial aircraft remains exceptionally resilient. The aerospace giant successfully booked 300 net commercial aircraft orders during the quarter, pushing its total commercial backlog to more than 6,300 planes, which are valued at a record-breaking $612 billion. Additionally, the company’s defense backlog climbed to a record $101 billion.
While Boeing clearly faces a much tougher road ahead compared to GE Aerospace—and its share price could potentially slip even further in the immediate term—Cramer remains fundamentally optimistic about the manufacturer’s longer-term prospects. That optimism, however, remains strictly contingent upon management’s ability to successfully execute its strategy and deliver reliably on its newly revised financial targets.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |