Wall Street’s Elite Drive Historic Equities Boom Amid Global AI Frenzy and Eased Regulations
Fueled by an unprecedented global boom in artificial intelligence stocks, newly relaxed capital rules, and an explosion in lending to hedge funds, the major Wall Street investment banks have already secured a banner year for equities trading with an entire quarter left to go.
According to comprehensive company filings, the five largest U.S. investment banks have generated a staggering $67 billion in equities revenue through September 30. This remarkable figure surpasses by $7 billion the total amount generated by the group during all of 2025, a period that was itself considered a record-shattering haul for the financial sector.
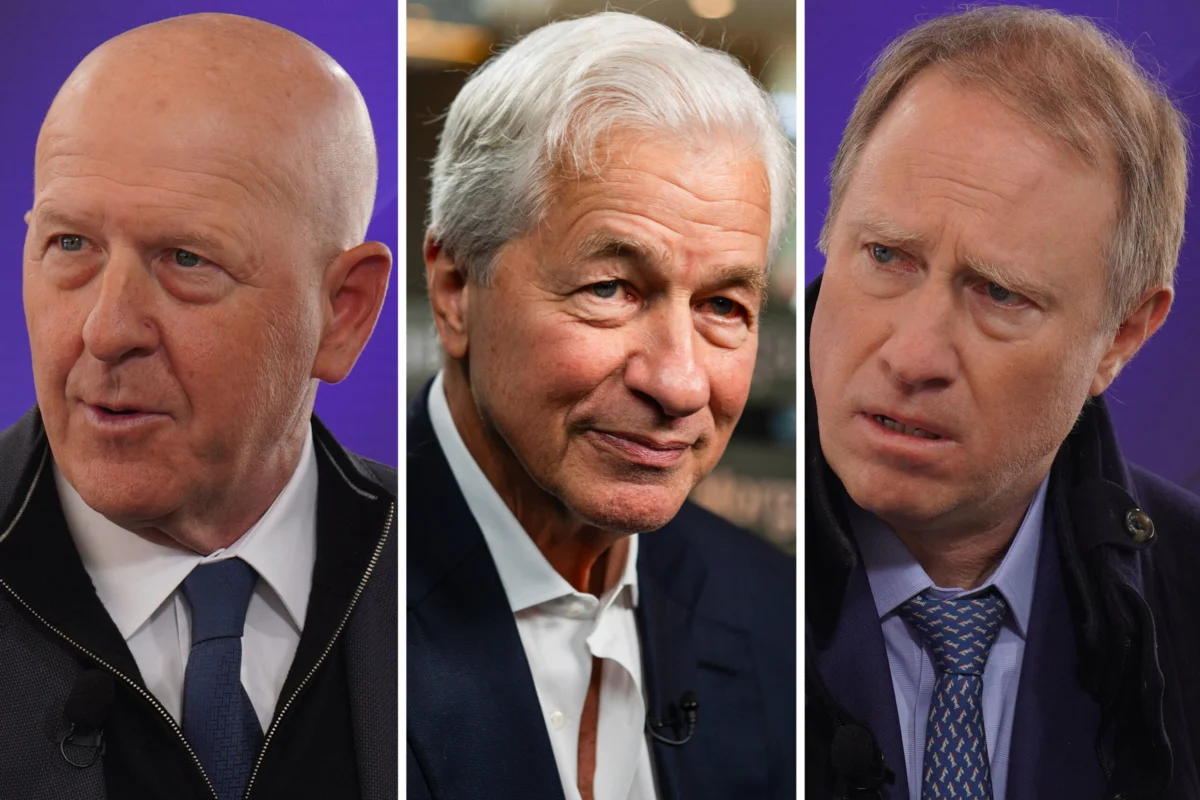
However, the vast majority of these profits have been captured by Wall Street’s "Big Three"—Goldman Sachs, JPMorgan Chase, and Morgan Stanley. Together, these three financial powerhouses have amassed a combined $52 billion in stock trading revenue so far this year, accounting for nearly 80% of the industry’s total haul.
"When it comes to the AI mega trade, the Big Three consider each other their main competitors, and that’s pretty much it," Mike Mayo, a veteran banking analyst at Wells Fargo, told CNBC. "They’ve been best positioned to take advantage of this market."
Across the financial district, major banking institutions are experiencing an epic run of blockbuster profits. This financial windfall coincides with a ballooning total market value for equities and a steady rise in trading activity from both institutional and retail investors across individual stocks, exchange-traded funds, and complex derivatives. A major catalyst driving this continuous market activity is the heavy influx of margin loans that banks are extending to hedge funds through their prime brokerage divisions, enabling these institutional investors to significantly amplify their financial bets.
Prime brokerage—the specialized business of supplying hedge funds with margin loans, securities lending, and other essential trading services—has rapidly transformed into a critical battleground and a primary source of corporate growth. The prime brokerage operations of the Big Three sit at the very center of the broader equities narrative because they cater to the largest funds operating across global markets and multi-asset products.
Demand for leverage to make massive bets on artificial intelligence hardware, hyperscale data centers, and advanced chip suppliers has reached unprecedented heights, according to comments made by bank executives. At Goldman Sachs, equities financing activities skyrocketed by 96% in the third quarter alone, reaching a record-breaking $3.37 billion. While competitors JPMorgan and Morgan Stanley do not break out that specific financing figure in their public earnings, executives at both firms noted that they experienced a strikingly similar market dynamic.
"I like your ‘insatiable demand for capital’ point. That feels about right," JPMorgan Chief Financial Officer Jeremy Barnum remarked during the bank’s third-quarter conference call, responding directly to analyst inquiries regarding accelerating financing demands.
"In this moment where AI is such an overwhelming theme… there is capital being tapped through all kinds of different mechanisms," Barnum added, emphasizing the sheer scope of liquidity moving through the markets.
That relentless demand has helped fundamentally transform equity trading desks at the Big Three from historically cyclical, transactional businesses into much more durable, high-margin lending engines, according to Wall Street executives. At the same time, the performance gap between these dominant giants and traditional rivals such as Bank of America and Citigroup highlights a rapidly widening divide within the broader capital markets.
"For clients, the value isn’t just a price on one trade, it’s coverage and continuity," Rachid Alaoui, JPMorgan’s global head of equities, told CNBC in a recent interview. "You want a dealer that can give you the full suite across products, and you want that service to travel with you across regions. That matters in stressed markets and periods of volatility."
Executing multibillion-dollar transactions, such as complex leveraged swaps on volatile artificial intelligence stocks or sector-specific exchange-traded funds, demands an extraordinarily robust balance sheet. The industry’s largest banks possess the financial capacity to absorb potential losses reaching $100 million without jeopardizing their quarterly financial results, according to senior trading executives. Conversely, smaller or more niche banks simply cannot underwrite single-trade risks of that magnitude, forcing them to turn away the business or permanently cede market share.
Furthermore, U.S. prime brokers have been significant beneficiaries of the strategic retreat of several European banks—including Credit Suisse, which was ultimately absorbed by UBS amid regulatory interventions—from the global equities business, noted Herman Chan, an analyst at Bloomberg Intelligence.
"Prime is one of the ultimate scale businesses," Chan explained. "If you have a strong equities franchise, the hedge funds will want to transact with you because you have a bigger pool of trading opportunities with counterparties."
Picks and Shovels
While domestic U.S. markets were largely captivated by software giants and cloud computing leaders throughout the year, senior trading executives note that the fastest-growing geographical frontier for equities trading was located in Asia. Institutional investors poured capital into South Korea and Taiwan, targeting the essential "picks and shovels" of the broader artificial intelligence supply chain, including the memory chipmakers and semiconductor manufacturers that are critical for constructing modern data centers, according to Alaoui.

For the Big Three, which maintain deep physical and operational footprints across Tokyo, Hong Kong, Seoul, and Mumbai, capturing the Asia trade proved to be a lucrative venture. Nevertheless, trading executives point out that local transaction taxes and stamp duties are frequently folded directly into top-line revenue figures, which can artificially inflate Asia prime brokerage totals.
Furthermore, because there is no standardized, universally agreed-upon definition of what constitutes equities trading revenue, some banking institutions include auxiliary business lines like clearing services, while others explicitly exclude them from their stock trading totals. This lack of uniformity makes direct, apples-to-apples comparisons across different institutions difficult.
Despite these accounting nuances, the underlying momentum of the business remains robust, heavily bolstered by a broader stock market rally that originally commenced in October 2022, just weeks before OpenAI publicly released ChatGPT.
"We’re still in a stock-based world," Morgan Stanley CEO Ted Pick stated during the firm’s earnings call. "Equities are still, all things being equal, the attractive asset class."
While the chief executives of both Goldman Sachs and Morgan Stanley have repeatedly emphasized that the artificial intelligence infrastructure build-out remains in its early years, financial analysts caution that if AI ultimately fails to be as transformative as currently anticipated, a sudden market downturn could impact these heavily exposed banks more severely than their peers.
The historic boom has also generated renewed scrutiny and concern regarding the potential systemic risks posed by heavily leveraged hedge funds. The International Monetary Fund issued a warning cautioning that growing leverage, increasingly crowded market positions, and correlated selling patterns among hedge funds could introduce significant financial stability risks. The IMF estimated that global hedge fund assets have climbed to a staggering $13 trillion.
In August, JPMorgan CEO Jamie Dimon noted that industrywide leverage was "the highest it’s ever been," though he stopped short of characterizing the risk as severe enough to pose an imminent threat to the broader financial markets.
Wall Street executives and market analysts were quick to point out that the financial industry easily absorbed the meltdown of several smaller hedge funds during the summer months. While the hedge fund run by former OpenAI researcher Leopold Aschenbrenner, known as Situational Awareness, garnered the lion’s share of media attention, several smaller investment firms also experienced forced unwinding events.
Prime brokers have grown increasingly adept at executing rapid margin calls and aggressively reducing risk exposure whenever markets move unfavorably against clients, Alaoui noted.
"In the summer, some investors had positions they were forced to unwind," he told CNBC. "They deleveraged, risk came down, and the market moved on."
‘Known Unknowns’
Another primary catalyst driving the ongoing equities boom is the regulatory shift implemented under the current administration. Regulators have moved to ease several strict financial-crisis-era leverage rules for the largest U.S. financial institutions, granting them substantially more operational room to expand balance-sheet-heavy operations, including prime brokerage services. These revised regulations were finalized in 2025, and major banks were permitted to adopt the looser standards as early as January.
By scaling back stringent balance sheet caps that historically treated safe assets like U.S. Treasurys and collateralized prime brokerage loans identically to much riskier corporate assets, regulators provided financial dealers with significantly greater flexibility to deploy balance sheet capital.
"Capital did go down, so you have to say the system is somewhat more levered because of the relaxation in regulations," said Darrell Duffie, a finance professor at Stanford University and a recognized expert on financial stability. "It’s not a good idea, but it hasn’t gotten dramatically out of whack."
The larger overall size of the market and heightened levels of volatility naturally generate increased trading volume, derivatives activity, and leverage, Duffie explained, though those developments are not inherently alarming on their own.
Senior Wall Street executives have similarly downplayed persistent concerns regarding systemic leverage, emphasizing that they rely heavily on rigorous collateral requirements and frequent, comprehensive stress testing to get ahead of potential operational problems before they cascade through the system.
"Hedge fund leverage as a contributor of risk to the system is very much in the category of known unknowns," JPMorgan’s Barnum stated. "It doesn’t mean it’s riskless, but we kind of know what it is."
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |