
Autumn Budget 2026: Chancellor Healey Delivers First Fiscal Statement with Mixed Measures for Small Businesses
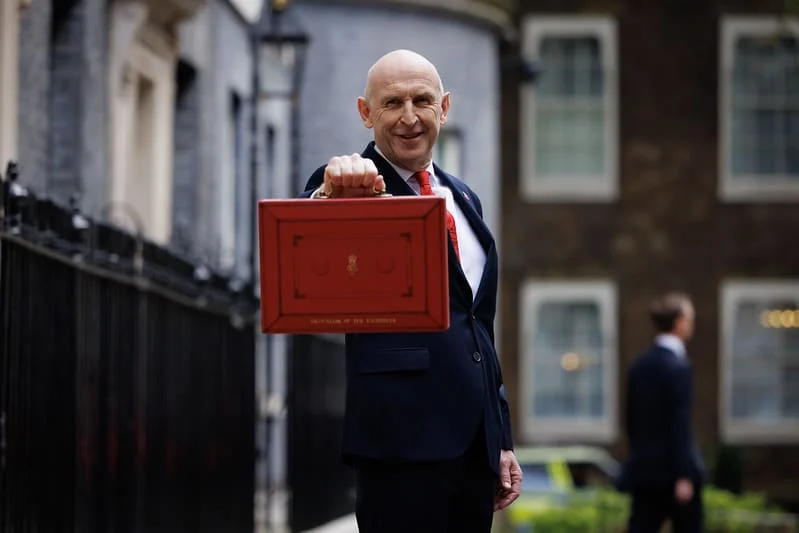
Chancellor Healey has stepped up to deliver his inaugural Budget, setting out a sweeping package of tax adjustments, regulatory updates, and public spending plans that will directly impact the UK’s small and medium-sized enterprise (SME) landscape. Coming against a backdrop of rising inflation, volatile gas prices, and tighter fiscal headroom, the newly unveiled fiscal statement attempts to balance broader economic growth goals with targeted relief for specific sectors. While the government has championed measures aimed at easing administrative burdens, supporting young founders, and expanding business rates relief, industry leaders have voiced significant concerns over escalating payroll costs and a continued heavy tax burden on foundational sectors outside of retail, hospitality, and leisure.
The Autumn Budget 2026 arrives as the Office for Budget Responsibility (OBR) upgrades its growth forecast to 1.2% this year and 1.6% by 2031, noting that the UK economy remains the fastest-growing in the G7. However, the OBR also highlighted pressures from rising inflation, noting that gas prices have nearly tripled since February, translating into higher running costs and loan rates for businesses. Against this complex economic backdrop, the Chancellor’s policy announcements have triggered an immediate and robust debate across the British business community.
Key Announcements Impacting Small Businesses
Young Entrepreneurs Allowance and Founders’ Relief
In an effort to stimulate enterprise and encourage early-stage risk-taking, the government has introduced a pilot Young Entrepreneurs Allowance. This initiative is designed to cover a full year’s worth of living expenses for young people launching new business ventures.
Complementing this at the higher-growth end of the spectrum is Founders’ Relief. Scheduled to take effect from April 2027, this policy will introduce a preferential 10% tax rate on lifetime gains of up to £10 million for the founders of what the Treasury describes as Britain’s most successful firms.
Higher Tax Threshold for Smaller and Side Businesses
Micro-entrepreneurs and side-hustle operators stand to benefit from a significant adjustment to the tax threshold for new enterprises. The point at which new businesses are required to pay tax will triple, rising from £1,000 to £3,000. This measure will be introduced through the Finance Bill 2026/27, with implementation slated for April 6, 2027.
Capital Investment and Full Expensing
Business investment incentives received notable updates. The current full expensing rules remain firmly in place to encourage long-term capital expenditure. However, minor adjustments accompany this continuation: the main rate of the writing down allowance will be reduced by two percentage points to 12% starting in April 2027, while the main rate of the First Year Allowance is set to increase from 40% to 50%.
Business Rates Reform and Sectoral Support
Business rates formed a central pillar of the Chancellor’s package, particularly for the retail, hospitality, and leisure (RHL) sectors. In England, the Small Business Rates Relief threshold for RHL properties is increasing from £12,000 to £18,000, effectively exempting an additional 70,000 businesses from business rates entirely. For larger RHL enterprises, the rate threshold for tapered relief will rise from £15,000 to £21,000. Both increases will take effect from April 2027, alongside a guarantee that there will be no above-inflation rate increases for any RHL business.
These provisions build upon the previously enacted 20% rate cut for pubs, clubs, and live music venues. Furthermore, the Transitional Relief Supplement is being extended by two years from April 2027. Conversely, Business Rates Relief will be stripped from vaping shops and adult gaming centres starting in April 2027, and the government is actively developing a General Anti-Avoidance Rule (GAAR) for business rates in England. Local authorities are also set to receive the option of implementing an Overnight Visitor Levy, often referred to as a tourist tax.
Supporting Small Business Scheme Extension
Businesses in England that previously received support under the 2023 Supporting Small Business Scheme will see the initiative extended for another year, beginning in April 2027.
Parental Pay and Wage Increases
Employment regulations will see structural updates over the coming years. For the first time, eligible self-employed fathers, partners, and adopters will become entitled to parental pay starting in April 2029.
Meanwhile, immediate cost pressures will arise from statutory wage adjustments. A 3.9% increase in both the National Living Wage and the National Minimum Wage has been confirmed, taking effect on April 1, 2027. The National Living Wage will rise by 3.9% to £13.21 per hour. For younger workers, the National Minimum Wage will increase by 3.9% to £11.27 per hour for 18 to 20-year-olds, and by 3.9% to £8.31 per hour for 16 to 17-year-olds and eligible apprentices. The accommodation offset will similarly rise by 3.9% to £11.53 per day.
Mototrist Tax Cuts and E-Invoicing
Tax provisions for business travel are being streamlined and enhanced. The 55p per mile rate covering the first 10,000 miles of car and van travel for work purposes is now permanent. Furthermore, the higher mileage rate applicable beyond 10,000 miles is being increased from 25p to 35p per mile. The freeze on fuel duty has likewise been extended until July 2027.
In the realm of digital administration, the government has laid out an implementation roadmap to make VAT e-invoicing mandatory from April 2029.
Red Tape Reduction and Online Marketplace VAT Liability
In an effort to ease administrative frictions, the government pledged to simplify public contract bidding processes for small businesses. Additionally, the Office for National Statistics (ONS) will streamline its business surveys to reduce the volume of data requests imposed on enterprises, introducing a new "Tell us Once" measure.
At the same time, tax enforcement is tightening within the digital economy. Online marketplaces such as Amazon and Temu will become legally responsible for collecting VAT on sales made by UK VAT-registered businesses, as well as any other UK business meeting a minimum annual sales threshold of £90,000 per platform. These rules will explicitly exclude personal sales, second-hand goods, and business-to-business transactions.
What the Experts Say
Reaction from the business advisory and advocacy sectors has been sharply divided, highlighting a tension between targeted sector reliefs and broader cost pressures facing employers.
Theo Chatha, chief financial officer at Bibby Financial Services, described the announcement as a bare minimum Budget that failed to deliver what most SMEs need to thrive. He noted that while support for retail, hospitality, and leisure is welcome, the wider SME economy—encompassing manufacturers, construction firms, wholesalers, hauliers, and service providers—remains burdened by high taxation without additional relief. Chatha also pointed to the cumulative effect of rising wages and previous employer National Insurance increases, warning that businesses are absorbing these costs without government assistance to help carry them.
Kevin Fitzgerald, UK managing director at Employment Hero, echoed sentiments regarding the mixed nature of the package. While welcoming business rates relief for a broader segment of SMEs, he cautioned that the 3.9% minimum wage increase would create nervousness among employers operating on tight margins. Fitzgerald emphasised that training and hiring support, particularly for apprenticeships, remains crucial for sustainable long-term business growth.
Adam Owens, head of tax for UK North and Midlands at Xeinadin, highlighted the immediate commercial risks of payroll expansion. He noted that higher payroll costs are guaranteed under mandatory wage hikes, whereas increased sales are not. For businesses with limited breathing room in their profit margins, this imbalance risks triggering higher consumer prices, staff reductions, or delayed investments.
Tina McKenzie, national chair of the Federation of Small Businesses (FSB), offered a sharply critical assessment, arguing that the Budget missed an opportunity to address soaring energy bills and high employment taxes. Citing FSB research showing that nearly half of small businesses expect shrinking revenues in the coming months, McKenzie asserted that the measures introduced fall short of altering a fundamentally gloomy outlook for independent enterprises.
Luke Cheetham, founder and CEO of uRisk Safety Services, suggested alternative approaches would have better served employment growth, advocating for a temporary employer National Insurance rebate for small businesses taking on additional staff during their first year of operation.
As the policy details from the Chancellor’s first fiscal statement are digested, attention will now turn to the legislative mechanics of the Finance Bill and how smaller enterprises navigate the combination of expanded digital compliance, administrative streamlining, and rising operational costs.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |