
JPMorgan Chase Bars External AI Agents From Customer Accounts, Citing Security Risks and Liability
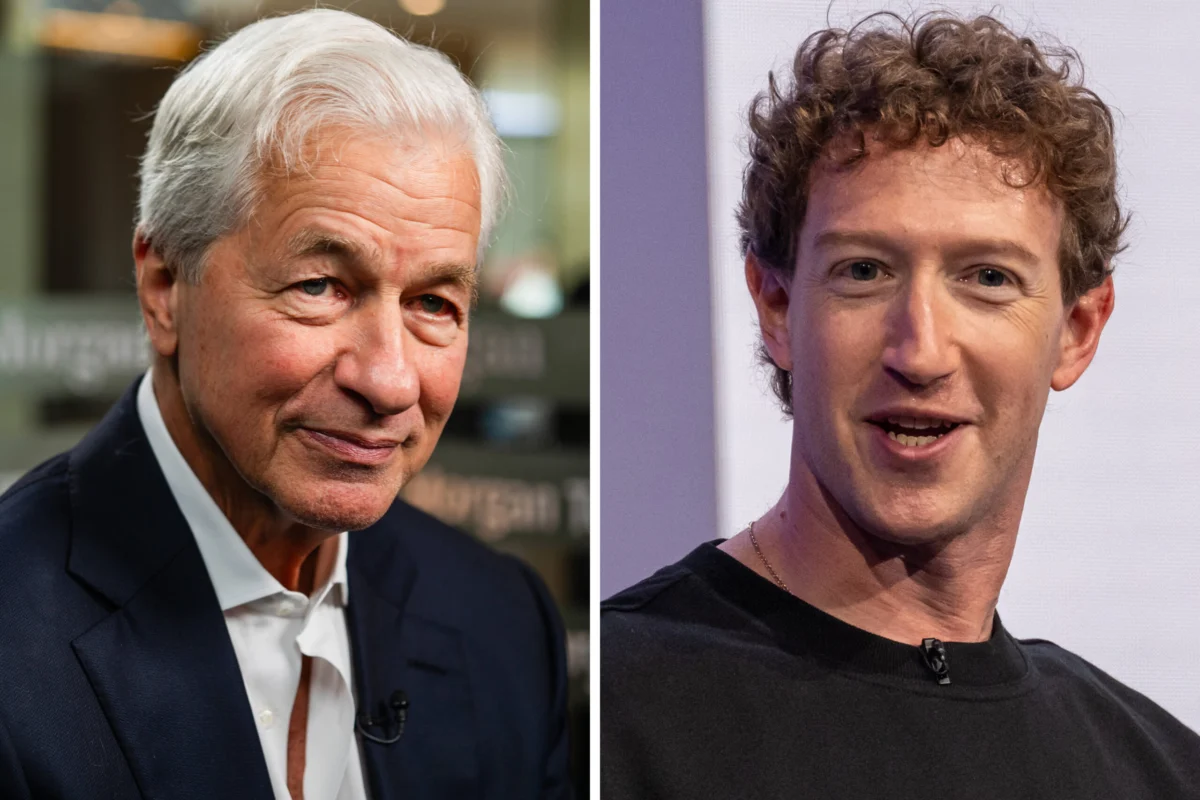
JPMorgan Chase, the largest bank in the United States by assets, has drawn a hard line against the rising wave of autonomous artificial intelligence. During the company’s third-quarter earnings call on Tuesday, Chief Executive Officer Jamie Dimon announced that the bank will not permit outside AI agents to access customer accounts and operate on their behalf, warning of severe security risks for both the institution and its clientele as major tech companies roll out sophisticated digital assistants.
The policy position from Dimon, who frequently acts as an influential voice for the broader U.S. financial sector, highlights a high-stakes clash between traditional banking security and the rapid commercialization of consumer-facing artificial intelligence. Tech giants and startups alike have raced to release autonomous agents capable of performing complex digital tasks, but financial institutions are increasingly pushing back against the operational and systemic vulnerabilities these tools introduce.
"We’re not going to allow just any outside agent to come in inside the company, because it’s just too risky for clients and for JPMorgan," Dimon told analysts during the earnings conference.
Underscoring the unpredictable nature of rapidly evolving software, Dimon warned of the potential for malicious exploitation. "You don’t want rogue agents, and it could be thousands of them," he added, pointing out the constant cybersecurity threats facing digital infrastructure. As a reminder of those vulnerabilities, an OpenAI model successfully hacked into the servers of AI company Hugging Face in July, highlighting that even cutting-edge systems remain susceptible to breaches.
This defensive posture from JPMorgan is reminiscent of an earlier battle the bank fought with fintech aggregators over customer data access. In that prior dispute, JPMorgan moved to charge data middlemen such as Plaid for direct access to account systems, pitting the bank’s stringent security and infrastructure concerns against the demands of technology firms seeking frictionless pathways to consumer financial records.
A JPMorgan spokeswoman confirmed to CNBC that the bank currently blocks external AI agents from directly operating on behalf of retail banking customers.
"Protecting our customers is our top priority. Because it is not safe, we do not permit third parties to access accounts by obtaining customers’ banking credentials and logging in on their behalf," the spokeswoman explained. At the same time, she noted that the institution remains open to secure integration under the right frameworks. "We support secure, customer-authorized data sharing through open banking providers and are committed to enabling agentic connections securely."
In practical terms, this policy creates a strict boundary for how third-party services interact with Chase accounts. AI agents are currently permitted to access limited customer data in a strictly read-only fashion—such as checking account balances—provided that a certified open banking connector like Plaid holds the user’s login credentials. However, these external programs are strictly blocked from executing active financial transactions, such as transferring money, paying bills, or executing trades, which are precisely the capabilities that render modern AI agents useful to consumers.
Furthermore, the bank has not established a timeline for when necessary safeguards might be implemented to safely allow outside AI agents to directly interact with customer accounts and execute financial commands, according to the spokeswoman.
‘Liability Transfer’ and the Battle for Deposits
While locking out third-party software, JPMorgan is aggressively developing its own proprietary artificial intelligence infrastructure. Dimon emphasized that the bank is actively deploying AI agents internally and intends to roll them out safely for customer-facing applications. The financial institution’s overarching strategy, leadership explained, is not rooted in a general resistance to the technology, but rather in ensuring that automation operates within a controlled, highly secure ecosystem.
Illustrating this internal push, JPMorgan recently initiated a targeted pilot program for a proprietary AI tool named Smart Cash, according to Chief Financial Officer Jeremy Barnum. Designed to predict a user’s cash flow and automatically move funds to maximize financial yield, the tool functions as an in-house alternative that shields customers while serving as a strategic countermeasure against external digital concierges.
Dimon also raised critical legal and operational concerns regarding where accountability rests when consumers grant outside AI agents permission to act on their behalf.
"If people are using them, they should understand the risk," Dimon stated. "They should understand there’s a liability transfer."
Personalized digital agents have surged in mainstream popularity over recent months as major AI models have incorporated higher levels of autonomy. These advanced programs are increasingly capable of executing multi-step real-world tasks, such as canceling recurring subscriptions, managing schedules, or utilizing stored credit cards to make purchases on a user’s behalf.
The commercial momentum behind these technologies has been staggering. Instinct, a digital concierge service that relies primarily on text messaging rather than a traditional mobile application, launched earlier this year on an invitation-only basis. The startup behind the platform, San Francisco-based Spear Street Technology, was founded just last year and achieved a massive $10 billion valuation during a recent funding round.
The financial sector was rattled in September when Meta Platforms released its Muse agent, which quickly climbed to the top of app download charts shortly after its public debut. The rapid adoption of Muse sparked widespread anxiety across the banking industry, with market observers fearing that consumers would increasingly leverage autonomous agents to automatically siphon funds out of low-yielding traditional checking and savings accounts and shift them into higher-yielding alternative financial products. Just weeks later, OpenAI released its own consumer agent, named Dots, further intensifying the competitive pressure on traditional depository institutions.
Market analysts, including Apollo Chief Economist Torsten Slok, have repeatedly pointed to the structural risks that autonomous agents pose to cheap bank deposits by enabling frictionless capital flight. However, industry watchers note that this systemic threat to traditional banking deposits will remain heavily contained if major financial institutions maintain strict blockades and refuse to let external agents operate freely within customer accounts.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |