
Financial Advisors Must Take Proactive Role in Identifying Client Cognitive Decline, Experts Say
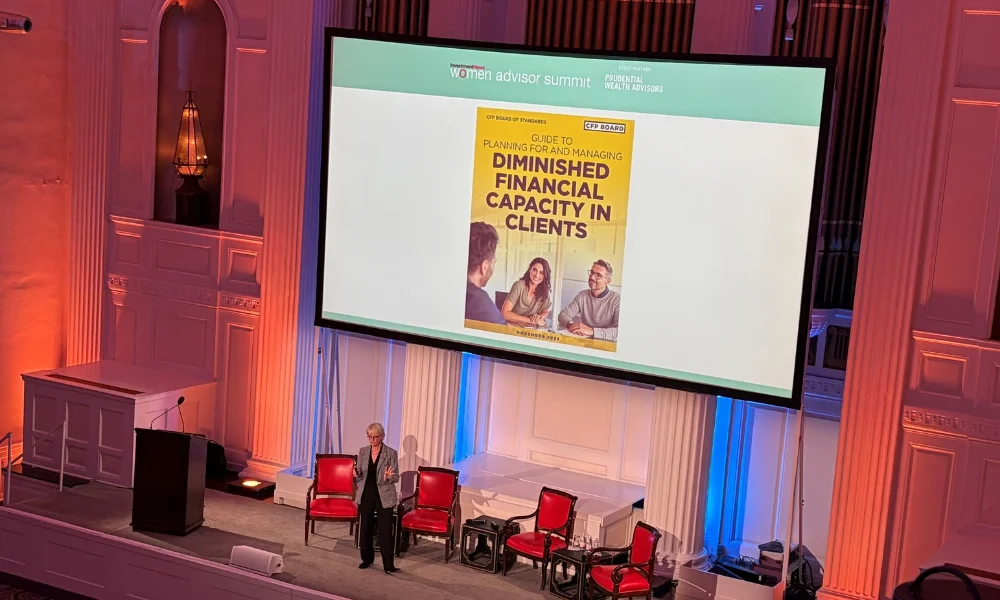
As the American population continues to age at an unprecedented rate, the role of the financial advisor is shifting from mere portfolio management to becoming a critical safeguard for client well-being. According to Carolyn McLanahan, a physician and the founder of Jacksonville, Florida-based Life Planning Partners, advisors stand on the front lines of a demographic shift, and they must be fully prepared to identify the early, often subtle, warning signs of cognitive decline among their aging client base.
Speaking at the recent InvestmentNews Women Advisor Summit, an event dedicated to elevating the standards and reach of financial planning, McLanahan emphasized that the stakes for failing to recognize these indicators are exceptionally high. For advisors who have spent decades building trust and managing the life savings of their clients, the onset of diminished capacity represents a significant professional and ethical hurdle. Because financial management is often one of the first cognitive functions to show signs of deterioration, advisors are frequently the first individuals outside of the immediate family to notice when a client begins to struggle with complex decisions, account management, or consistent logic.
"What we do know is that financial management skills are the first to go," McLanahan told attendees. "So it is important that in your office, everybody be trained on how to recognize an issue."
The urgency of this message is underscored by the current trajectory of the U.S. population. Data from the 2020 U.S. Census highlights the scale of the challenge: one in six Americans is now aged 65 or older. Furthermore, the census data reveals that the demographic segment aged 65 and over grew by 38.6% between 2010 and 2020, reaching a total of 55.8 million individuals. This represents the fastest rate of growth for this age group since the decade spanning 1880 to 1890. As this massive cohort enters their later years, the financial advisory profession is facing a reality where cognitive health is no longer a peripheral concern but a central pillar of comprehensive financial planning.
McLanahan, who was honored with the Alexandra Armstrong Lifetime Achievement Award by InvestmentNews in 2024 for her contributions to the field, argues that reactive measures are insufficient. "We have to identify it early—once you identify it, you can’t sit on it," she noted. When an advisor notices a client repeating questions, missing appointments, showing confusion regarding basic account statements, or exhibiting sudden changes in their risk tolerance or investment philosophy, the time for subtle observation has passed, and the time for structured intervention has begun.
A cornerstone of this preparedness, according to McLanahan, is the mandatory use of a "trusted contact" form for every client. This is a procedural safeguard that she believes should be integrated into every estate planning review. The trusted contact—a person authorized by the client to be contacted by the firm if there is a reasonable suspicion of financial exploitation or if the firm is concerned about the client’s cognitive health—acts as a vital bridge between the advisor and the family. "You do it during the estate planning review," McLanahan advised. "Once serious cognitive decline steps in, good luck if you haven’t prepared."
The complexity of navigating these situations has led industry bodies to step in with standardized guidance. McLanahan, who serves on the CFP Board Resource Commission, pointed to the organization’s ongoing efforts to provide advisors with the tools they need to manage these sensitive transitions. The "Guide to Planning For and Managing Diminished Financial Capacity in Clients," published by the CFP Board, serves as a primary resource for practitioners. It offers a framework for identifying red flags, recognizing the signs of potential financial exploitation—to which the elderly are particularly susceptible—and determining the best practices for managing the advisor-client engagement once diminished capacity becomes apparent.
However, beyond the procedural and regulatory requirements, McLanahan believes that advisors must engage in much broader, more humanistic conversations with their aging clients. She advocates for a holistic approach to the aging process, urging advisors to move beyond balance sheets and market performance to discuss the actual logistics of living as one ages.
One of the most provocative pieces of advice McLanahan offers is to encourage clients to physically visit the facilities where they might eventually need to reside. Her firm frequently arranges visits to nursing homes and assisted living facilities, turning what could be a frightening hypothetical into a tangible, manageable reality. "The nursing home is actually very excited that people are coming to visit—they actually provide lunch and we get a tour," she said. By demystifying these facilities, advisors can help remove the stigma and fear associated with long-term care, allowing for more productive planning conversations.
These conversations must also extend to the delegation of authority. McLanahan stresses that advisors need to help clients answer the difficult questions of "who" and "how" before the necessity arises. This includes identifying specifically who will be responsible for making financial decisions when the client no longer can, as well as who will be empowered to make healthcare decisions. These are not merely legal questions; they are relational ones that require the client to trust their family members or fiduciaries with significant power.
Transportation is another often-overlooked area of long-term planning that McLanahan insists must be addressed. In many parts of the United States, especially in suburban or sprawling regions like her home base of Jacksonville, Florida, the ability to drive is synonymous with independence. When that independence is lost, the impact on a client’s quality of life can be devastating. "Where I live in Jacksonville, Florida, you can’t get around without a car—and so having a conversation about ‘what are you going to do if you can’t drive’?" is essential, she explained.
By having these candid, sometimes uncomfortable, conversations early, advisors can better prepare for the financial implications of long-term care. When a client has a clear plan for where they will live, who will support them, and how they will navigate their community, the advisor is in a much stronger position to forecast the necessary costs and structure the portfolio to support those needs.
The goal of this comprehensive planning is not merely to protect the advisor from liability or to protect the client’s assets from exploitation, but to ensure that the client maintains their dignity and autonomy for as long as possible. As the population continues to age, the ability to shepherd clients through the transition into their later years will become a defining skill for the modern financial advisor. By fostering a culture of alertness, utilizing formal tools like trusted contact forms, and facilitating honest conversations about the realities of aging, advisors can provide a level of service that goes far beyond traditional investment management, ensuring that they are true partners to their clients throughout the entirety of their lives.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |