The "Underground" RIA Market: Steward Partners Executives Argue M&A Activity is Vastly Underreported
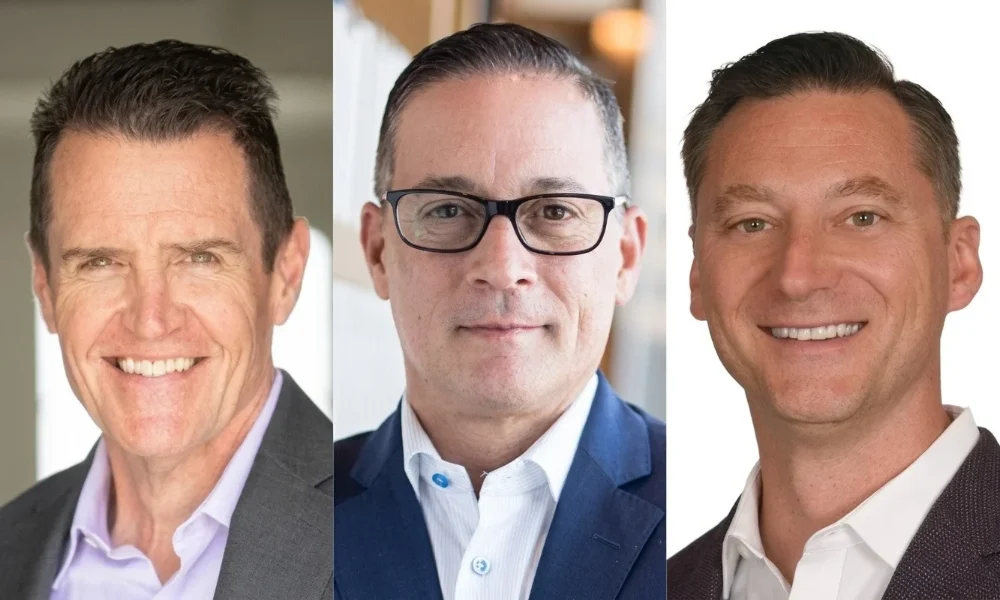
The registered investment advisor (RIA) industry has long been defined by its M&A headlines—massive, billion-dollar acquisitions, private equity-backed rollups, and high-profile deals involving national wealth management powerhouses. However, according to executives at Steward Partners, a prominent hybrid RIA managing $57 billion in client assets, the narrative captured by industry analysts and consultants represents only a fraction of the actual transactional activity taking place.
Jim Gold, CEO of Steward Partners, suggests that RIA deal activity is currently running at three to five times the volume documented by industry trackers. Gold characterizes this unseen movement as an "underground" market, primarily driven by advisor-to-advisor sales, internal succession planning, and smaller book buyouts that fly under the radar of traditional reporting mechanisms.
The Disconnect Between Reported Data and Market Reality
Publicly, the RIA M&A landscape is tracked by specialized investment banks and consultancies that provide essential benchmarks for the industry. DeVoe & Company, for instance, reported a record-setting 322 RIA deals in 2025 and 244 through September 2026. While the firm noted a 17% year-over-year decline in volume during the third quarter of 2026, the overall pace remains historically robust. Similarly, M&A consultancy Echelon Partners tracked 466 RIA deals in 2025.
The discrepancy, according to Gold, lies in the methodology. Firms like DeVoe focus heavily on announced mergers and acquisitions, while Echelon’s broader scope accounts for capital infusions, restructurings, and breakaway transactions. Yet, even with these more comprehensive models, Gold argues that the vast majority of smaller, private transactions remain entirely absent from the conversation.
"If your transaction is not directly tied to an investment bank of some sort, no one reports on it," Gold told InvestmentNews. "I think the number is probably 300% of what we’re seeing out there. I think the numbers are literally three, four, or five times what’s being reported publicly."
The issue is one of visibility. For many small-to-mid-sized RIAs, a succession plan or the sale of a client book is a private arrangement between colleagues or a transition managed internally within a firm. Because these deals lack the institutional complexity of a private-equity-backed acquisition, they do not trigger the press releases or regulatory filings that analysts use to build their databases.
Life Off the Books
Steward Partners serves as a prime example of this phenomenon. Despite its substantial scale, the firm frequently engages in transactions that never make a headline. These include internal acquisitions where tenured advisors elect to sell their books to the firm or engage in peer-to-peer arrangements facilitated by internal succession groups.
"You have M&A where we’re acquiring advisors at our firm, who are coming to us and saying, ‘Hey, I’ve been here 10 years, I want to sell my book to the company,’" Gold explained. "There’s a ton of peer-to-peer M&A going on. Many of these independent firms have a succession group where they’re basically playing matchmaker and pairing up advisors to buy each other’s books out, and none of this is reported."
Jeff Gonyo, head of wealth management at Steward, notes that the firm logged 16 to 17 publicly reported deals over the past 12 months, yet these were accompanied by roughly a dozen internal transactions that went unannounced. For Gonyo, this is not an anomaly limited to Steward; it is an industry-wide standard.
"That movement is happening constantly, and we’re just a microcosm of that," Gonyo said. "Anything under that $100 million AUM mark is not getting picked up anywhere. And if you think about the size of the RIA industry, the majority of RIAs live in that lower volume space."
The implications for the broader industry are significant. If the vast majority of deal activity happens at the sub-$100 million level, the "industry trend" reports currently shaping the market are effectively ignoring the lifeblood of the independent advisory space.
The Skewed Perception of RIA Valuations
The lack of reporting on these smaller transactions does more than just undercount deal volume; it distorts the perception of what an RIA firm is worth. In December 2025, Steward Partners secured $475 million in strategic capital from Ares, a move that placed the firm squarely within the high-stakes world of institutional-grade valuations. However, Joseph Glick, who has served as Steward’s chief operating officer since July 2026, believes that industry-wide benchmarks for valuations are fundamentally skewed by the absence of data from smaller, private deals.
"Deal terms are only disclosed for your larger marquee deals," Glick noted. "You won’t see those deal terms being floated around for some of these smaller deals or succession planning that we’re doing with other firms."
Current data paints a picture of an industry where prices are consistently reaching new highs. Fidelity, for example, recently reported that the median size of acquired RIAs increased from $517 million to $630 million in the first half of 2026 compared to the same period in 2025. Furthermore, the Advisor Growth Strategies annual RIA Deal Room Report found that the median multiple paid for RIA firms hit 11.6x EBITDA in 2025, marking the highest level on record.
Glick argues that these figures are misleading when applied to the entire industry. Because the data is heavily weighted toward the "marquee" deals—those involving institutional buyers and massive, billion-dollar firms—they do not necessarily reflect the reality for the average advisor looking to retire or exit their practice.
"Some of the deal terms that we’re seeing bandied around in terms of valuation multiples and things of that nature, it’s largely for bigger firms that are being acquired by scaled acquirers," Glick said. "Some of the deal terms that we’re seeing, I would say, aren’t necessarily representative of the entire market."
This creates a "valuation gap" in perception. Advisors at smaller firms, seeing the record-breaking multiples reported in the financial press, may develop unrealistic expectations for their own exit strategies. Conversely, they may feel discouraged if they perceive that only firms of a certain size are "marketable."
As the RIA industry continues to consolidate, the divide between the hyper-visible, private-equity-backed mega-firms and the quieter, yet massive, base of smaller, independent practices seems likely to grow. For executives at firms like Steward Partners, the priority is ensuring that the industry recognizes that the "official" numbers are only half the story. Until a mechanism exists to capture the internal successions and advisor-to-advisor transfers that define the daily operations of thousands of firms, the true health and valuation landscape of the RIA market will remain, to some extent, an open secret.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |