Berkshire-Backed Bending Spoons Emerges as a Tech Acquirer Amid the ‘SaaSpocalypse’
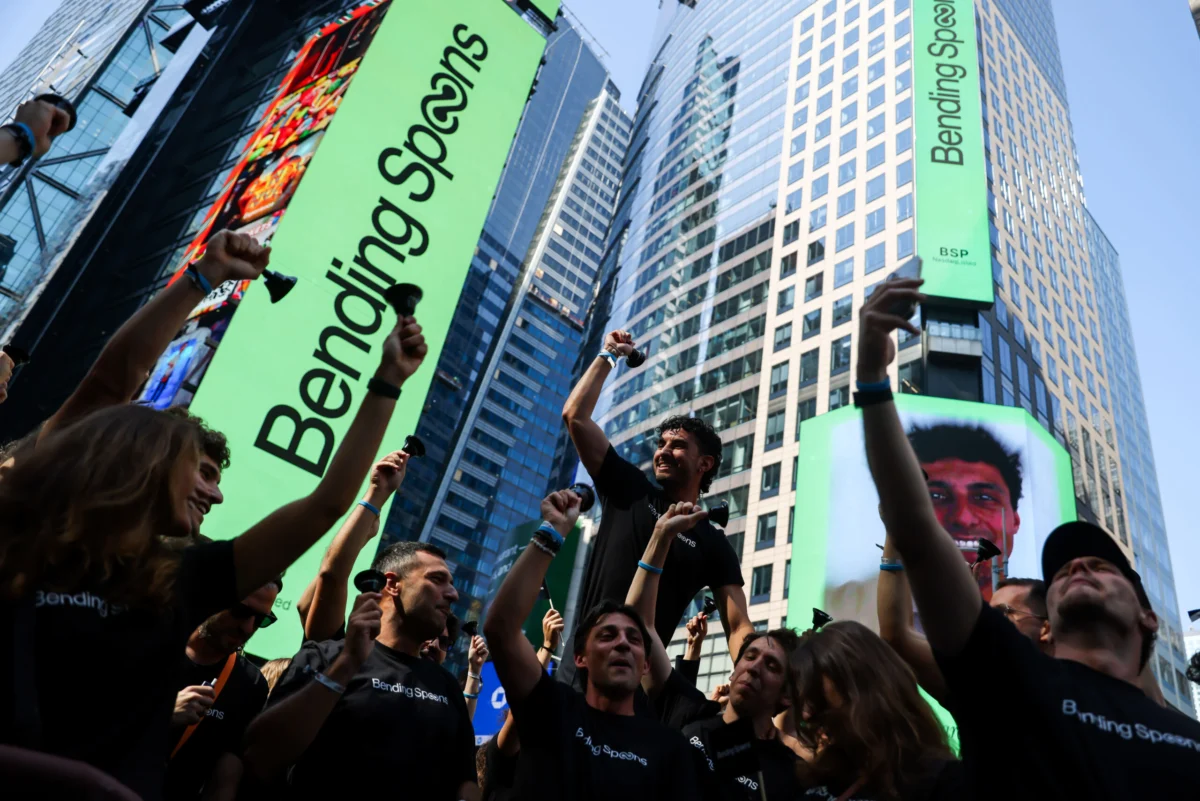
Less than four months after its high-profile public debut on the Nasdaq, Milan-based holding company Bending Spoons has emerged as an unlikely sanctuary for former high-flying software startups displaced by the artificial intelligence boom. Its aggressive merger and acquisition strategy received a major validation this week when Berkshire Hathaway—a corporate entity long cited by Bending Spoons leadership as a primary inspiration for its business model—deepened its financial commitment to the firm.
Berkshire Hathaway disclosed an additional $330 million investment on Wednesday, bringing its total stake in Bending Spoons to over $900 million. Wall Street responded enthusiastically to the news, initially sending Bending Spoons’ stock up 41% before some of those gains moderated later in the week, leaving the company with a market capitalization of approximately $30 billion.
Analysts at Mizuho highlighted the significance of the vote of confidence in a note following the announcement, writing that Berkshire’s decision to add to its position just months after the initial public offering and at current valuation levels provides a powerful endorsement of the Bending Spoons model from one of the world’s most respected long-term investors.
At the time of its Nasdaq debut in July, Bending Spoons was largely viewed as a little-known European holding company housing older internet brands such as AOL, Vimeo, Eventbrite, and Evernote. Today, it sits at the center of a rapidly shifting technology landscape defined by the artificial intelligence revolution.
The flipside of Bending Spoons’ rapid acquisition strategy, however, has involved significant workforce reductions. In August, the company announced it was acquiring workflow software provider Airtable for roughly $1.3 billion—a price tag representing a discount of nearly 90% compared to Airtable’s peak valuation in late 2021. On Monday, Bending Spoons confirmed that a large portion of Airtable’s pre-acquisition team would be departing with substantial separation packages. Similar layoffs were previously implemented across other portfolio holdings, including Evernote, Vimeo, and WeTransfer.
For the broader technology sector, Bending Spoons’ aggressive maneuvers underscore how quickly market fortunes are reversing in the AI era. As advanced agents powered by large language models developed by entities like Anthropic and OpenAI march toward trillion-dollar valuations, businesses are increasingly placing critical operations into the hands of AI, often at the expense of traditional software-as-a-service providers. This phenomenon, which has swept across the industry, is increasingly referred to by market participants as the "SaaSpocalypse."
Publicly traded software names such as Intuit, HubSpot, and Adobe have all seen their shares decline by at least 30% this year. Meanwhile, a long list of private SaaS companies that once enjoyed darling status among venture capitalists are now struggling to secure fresh capital as the public markets show little appetite for traditional tech initial public offerings. Reflecting this distressed environment, Bending Spoons agreed last month to acquire collaboration software vendor Miro—which was once valued at $17.5 billion—for just $1.36 billion.
Ethan Kurzweil, founder and managing partner at Chemistry VC and a veteran software investor, noted that market sentiment has become starkly binary. Observing that he uses Airtable himself and recognizes the presence of many sound SaaS products built by solid teams, Kurzweil pointed out that these companies simply occupy a different tier of the market. In the current environment, he explained, market participants view businesses as either exceptionally hot or completely obsolete.
An App Turned Acquirer
Bending Spoons was originally founded in 2013 by Luca Ferrari, who serves as chief executive officer, alongside Matteo Danieli and Francesco Patarnello. The trio initially attempted to launch a mobile application called Evertale, which failed to gain meaningful traction. Rather than continuing to push products that consumers did not want, the founders decided to use the remaining $40,000 of their capital to build an operating company instead, according to the firm’s IPO prospectus.
The company has executed its most prominent acquisition deals over a compressed timeline, beginning with the purchase of Evernote in 2022, followed by Brightcove in 2024, and subsequent acquisitions of Vimeo, AOL, and Eventbrite across 2025.
Bending Spoons formally entered the public markets on June 30, raising approximately $1.7 billion by pricing its shares at $29 each before beginning trading on the Nasdaq the following day. The stock closed the week at $47.07.

Prior to Bending Spoons’ recent pivot toward enterprise software, the corporate landscape for software acquisitions was heavily dominated by private equity giants such as Thoma Bravo and Vista Equity Partners. Those traditional private equity firms typically targeted undervalued SaaS companies, utilizing cost cuts, efficiency enhancements, and corporate rollups to transform them into assets that could eventually be sold or taken public at elevated valuations.
Bending Spoons, by contrast, operates under a different strategic playbook. Rather than pursuing eventual exits, the Milan-based firm aims to generate long-term profits directly from the businesses it acquires, drawing a parallel to the classic Warren Buffett model. However, unlike Berkshire Hathaway, Bending Spoons focuses exclusively on technology and maintains a deeply hands-on approach regarding software development, operational adjustments, and personnel decisions.
Nick Mehta, the former CEO of cloud software vendor Gainsight—who sold his company to Vista Equity Partners in 2020—remarked that traditional private equity firms currently face severe operational constraints because they paid elevated prices for past deals and now manage portfolios of troubled assets. According to Mehta, these firms find it difficult to execute bold new strategies because their investors want liquidity, yet the broader market features few willing buyers for legacy tech assets built before the advent of generative AI.
Neither Thoma Bravo nor Vista Equity Partners responded to requests for comment. Bending Spoons told CNBC in a statement that it has not been outbid for an acquisition target in several years. As the firm aggressively expanded its footprint into SaaS, Mehta noted that "Bending Spooned" has transformed into a colloquial verb in Silicon Valley, describing companies that are acquired for pennies on the dollar.
Lloyd Walmsley, an analyst at Mizuho, emphasized that Bending Spoons distinguishes itself from traditional buyout firms through the depth of its operational involvement. Pointing to the company’s willingness to implement substantial product changes, Walmsley noted that traditional private equity firms rarely introduce changes of a comparable magnitude.
For end users of the software platforms acquired by Bending Spoons, these operational overhauls often translate into immediate price increases. In April 2023, several months after acquiring Evernote, Bending Spoons raised the annual subscription price for personal accounts from $70 to $130. The company subsequently restructured its pricing tiers, introducing a starter plan priced at $100 and an advanced plan costing $250, replacing previous pricing models.
Walmsley recalled that his initial personal reaction to the price increase was to consider switching to Microsoft’s note-taking application, OneNote. Ultimately, however, he chose to remain an Evernote subscriber. Explaining the dynamics of the firm’s portfolio strategy, Walmsley noted that Bending Spoons is exceptionally skilled at identifying products that deliver high inherent value where customer switching costs are prohibitive, allowing them to raise prices effectively without driving away their core user base.
CEO Luca Ferrari stated in an interview that the overwhelming majority of the profits generated by portfolio companies are reinvested into future growth, primarily through additional dealmaking. He explained that the firm identifies specific opportunities for operational improvement that can be unlocked over the first few years of ownership, after which the businesses operate according to the organic growth dynamics intrinsic to their respective markets.
For Berkshire Hathaway and other investors backing Bending Spoons, the long-term viability of this strategy remains unproven. The acquired products must retain sufficient market desirability to convince customers to absorb higher prices at a time when artificial intelligence is compressing profit margins across the broader software industry.
During its first earnings report as a public company in August, Bending Spoons reported that revenue more than doubled year-over-year to exceed $700 million, with growth driven almost entirely by recent acquisitions, while net income climbed 171% to $177 million. These financial results were reported prior to the closure of the Airtable transaction and the announcement of the Miro acquisition. In the coming quarters, Wall Street will closely monitor whether the company’s unique operational structure can successfully sustain and revitalize legacy software assets.
Addressing analysts on the August earnings call regarding whether the Airtable acquisition signaled a permanent strategic shift toward enterprise software, Ferrari noted that approximately half of Bending Spoons’ revenue already originated from professional businesses, largely through Brightcove and Vimeo. He explained that the recent emphasis on enterprise software was driven primarily by market valuation realities following a severe market correction, adding that the firm historically viewed the valuations of most enterprise SaaS businesses as irrationally inflated.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |