
The Silent Crisis: Why Rising Healthcare Costs are Leaving Retirees Exposed
For most Americans, retirement planning is dominated by conversations about portfolio growth, tax efficiency, and the ideal age to claim Social Security benefits. Yet, a looming, often ignored variable threatens to dismantle even the most robust financial strategies: the escalating cost of healthcare. According to a survey released in March 2026 by D.A. Davidson, only 16% of Americans feel they possess a deep understanding of what their healthcare will actually cost once they leave the workforce. This knowledge gap represents a dangerous blind spot, leaving many households exposed to what financial advisors now identify as one of the most significant and volatile line items in a retirement budget.
The survey, conducted online by Big Village between February 13 and 15, 2026, polled 1,006 U.S. adults and revealed a stark disconnect between anxiety and action. While 78% of respondents expressed genuine concern about the impact of rising medical costs on their golden years, less than half—just 48%—have formally incorporated these expenses into their financial planning. Perhaps more concerning is the lack of professional guidance sought on the matter; only 23% of participants have ever broached the subject with a financial advisor. The urgency of this issue is underscored by personal experience, as six in 10 respondents noted they have already witnessed a friend or family member struggle to manage the financial burden of care during retirement.
The math behind these concerns is increasingly daunting. Fidelity Investments’ latest Retiree Health Care Cost Estimate suggests that an average 65-year-old couple retiring in 2026 should prepare for a lifetime healthcare bill of approximately $185,500. This figure represents a 7.5% increase from the previous year—a sharp climb that excludes the potentially catastrophic expenses associated with long-term care. As inflation in the medical sector consistently outpaces the broader Consumer Price Index, these estimates are likely to remain on an upward trajectory, forcing retirees to navigate a landscape of rising premiums, co-pays, and out-of-pocket prescription costs.
Why Clients Delay Retirement Healthcare Planning
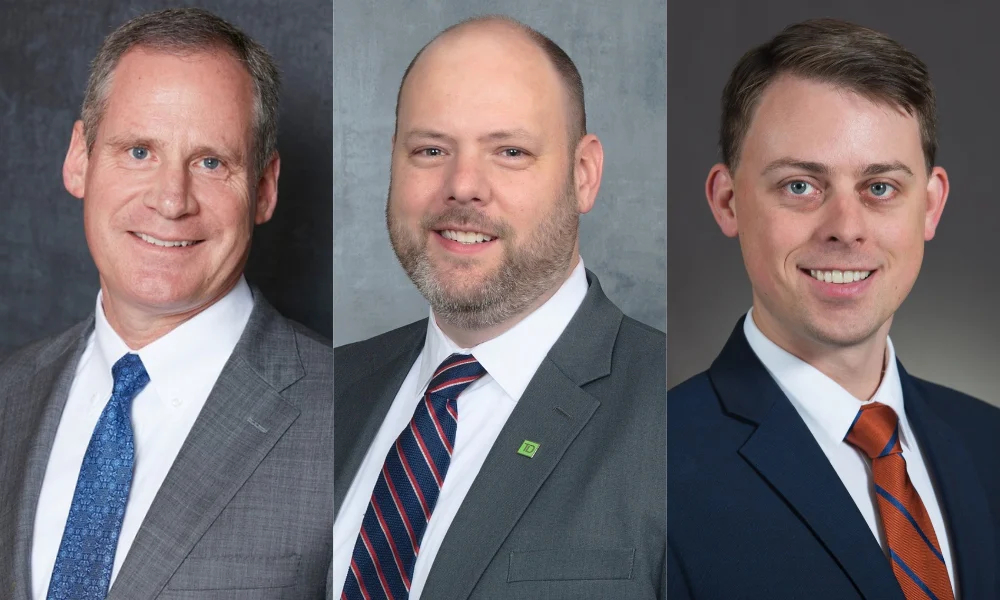
The reluctance to plan for future health costs is not merely a result of oversight; it is a complex psychological and logistical hurdle. Andrew Crowell, a financial advisor and vice chairman of wealth management at D.A. Davidson, observes that younger, healthy clients often struggle to visualize a "worst-case scenario." When the future feels distant and physical health is currently robust, it is easy to relegate healthcare planning to the bottom of the priority list.
"I see it all the time," Crowell says. "But waiting too long to plan for future healthcare expenses can severely impact a retirement strategy. One of the best tools we have against far-off costs like these is the power of compound interest over time." Crowell emphasizes that savers often underestimate the impact of consistent, incremental contributions. He argues that even small, disciplined amounts—such as $25 a month—invested strategically, can begin to build a buffer against the persistent pressure of medical inflation.
Ashley Weeks, a wealth strategist at TD Wealth, attributes the lack of urgency to the pressure of immediate financial obligations and a pervasive, often dangerous, misunderstanding of the federal safety net. Many Americans hold the incorrect assumption that Medicare will provide comprehensive, affordable coverage for all their needs. This reliance on a system that is not designed to cover every medical contingency can, in Weeks’ view, derail an otherwise sound and thorough financial plan.
For Peter Hoglund, senior vice president and financial advisor at Wealth Enhancement Group, the hesitation is deeply emotional. The topic of late-life healthcare is fraught with uncertainty regarding the duration, intensity, and cost of care, making it an intimidating subject for many clients. "Families that have seen the nightmare health scenario play out firsthand, usually with a parent or loved one experiencing a healthcare event, are able to prepare for this with more clarity," Hoglund notes. "But it can also become an outsized fear and cause under-preparedness in the rest of the financial plan."
What Medicare Leaves Uncovered
The assumption that Medicare acts as a total shield against medical costs is one of the most common pitfalls in retirement planning. Medical inflation typically runs at least double the rate of general inflation, meaning that current estimates for co-pays, prescription drugs, and hospital stays often understate what retirees will face in the future.
Beyond basic coverage gaps, higher-income retirees face a specific, often overlooked hurdle: the Income-Related Monthly Adjustment Amount, or IRMAA. This is a surcharge added to Medicare Part B and Part D premiums once a retiree’s income exceeds specific thresholds. As of 2026, the standard Part B premium has risen to $202.90 a month—an increase of $17.90 from the previous year. However, for individuals with a modified adjusted gross income of $500,000 or more, that monthly cost jumps to $689.90. For high-net-worth clients, failing to account for these surcharges can lead to significant budgetary shocks.
To combat this, advisors are increasingly turning to advanced planning software. These tools allow for a more personalized projection of spending by factoring in a client’s specific health status, family history, geographic location, and life expectancy. By modeling out-of-pocket spending both before and after Medicare eligibility begins, advisors can provide clients with a more realistic, data-driven roadmap.
How Can Advisors Use HSAs to Fund Retirement Healthcare Costs?
Among the tools available to combat these costs, the Health Savings Account (HSA) stands out for its unique tax advantages. An HSA allows individuals enrolled in high-deductible health plans to contribute pre-tax dollars, invest those funds tax-free, and withdraw them tax-free for qualified medical expenses—the so-called "triple tax advantage." For the 2026 tax year, the IRS has set contribution limits at $4,400 for self-only coverage and $8,750 for family coverage, with an additional $1,000 "catch-up" contribution allowed for those aged 55 and older.
"Medical costs tend to climb faster than overall consumer prices, and as we age, we typically need more care each year," says Weeks. He encourages eligible workers to maximize these contributions and, crucially, to invest the account balance rather than holding it in a low-yield cash account. Despite these benefits, many savers leave this potential untapped. Fidelity has found that 40% of HSA holders have not invested their balances, treating them instead as a revolving door for current expenses rather than a long-term retirement vehicle. Similarly, only 13% of D.A. Davidson’s survey respondents identified HSAs as a planned source of retirement healthcare funding, suggesting a major disconnect between available tools and public awareness.
This lack of focus on healthcare funding may also stem from shifting workplace priorities. Recent research from Morgan Stanley indicates that 401(k) retirement plans now rival healthcare benefits as the most valued perk for workers, shifting the focus of many employees away from immediate health-account optimization. Hoglund adds a note of caution, reminding clients that while HSAs are powerful, they have limitations. The annual contribution caps are relatively modest compared to the potential magnitude of late-life medical bills, meaning that while an HSA is an essential piece of the puzzle, it is rarely the only one required.
Stress-Testing the Plan for a Healthcare Shock
The path forward, according to advisors, is to move beyond general projections and toward "stress-testing" a financial plan. Hoglund recommends that clients model a major health event—such as a sudden diagnosis or the need for extended care—to determine exactly where their financial structure might break.
"Building in the potential for a healthcare event that adds significant expense and understanding what the net result of this can provide clarity and takes away the uncertainty of the unknown surrounding potential healthcare cost," Hoglund says. Once a client sees the impact of a worst-case scenario on their assets, they can make informed decisions regarding long-term care insurance, increasing HSA contributions, or designating specific "medical-only" funds within their portfolio.
Timing, particularly regarding insurance, is vital. Advisors emphasize that waiting until one is older or facing health challenges to seek long-term care insurance or supplementary coverage often results in higher premiums or, in some cases, a total loss of eligibility. Crowell notes that the most effective way to secure these protections is to act while the client is still young and healthy.
Ultimately, the goal is to shift the narrative from fear to preparation. With only 23% of Americans currently discussing these concerns with an advisor, the potential for improvement is vast. Research from the TIAA Institute suggests that retirees who engage with a financial advisor report far fewer regrets, yet only one in four Americans currently utilize such services. As Crowell concludes, while preparing for rising healthcare costs is a major financial undertaking, being informed remains the first and most critical step in ensuring that the final years of retirement are marked by security rather than financial strain.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |