
Starbucks Reports Mixed Fiscal Q4 Results as Strong U.S. Turnaround Counters International Underperformance
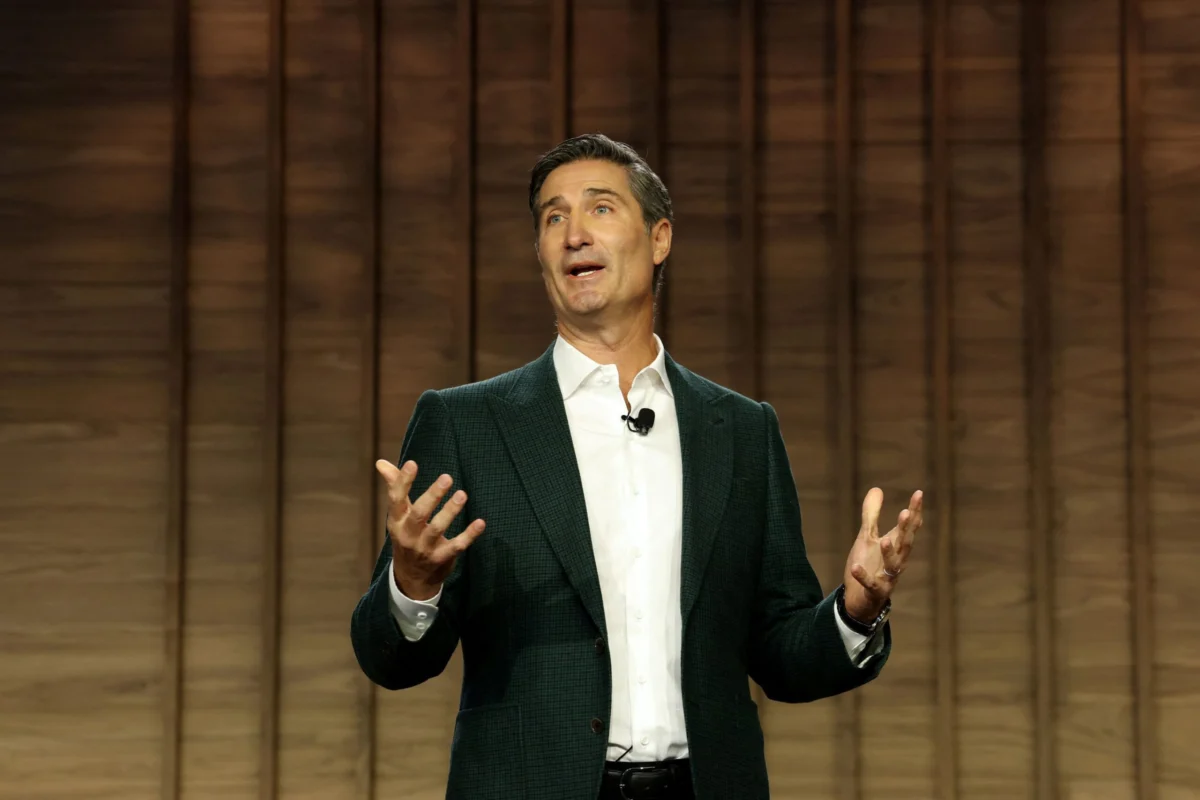
Starbucks reported mixed financial results for its fiscal fourth quarter on Thursday, as a robust domestic turnaround helped offset underperformance across its international café portfolio. The coffee giant’s performance in its home market topped expectations during the final quarter of fiscal 2026, signaling that Chief Executive Officer Brian Niccol’s strategic overhaul is continuing to gain traction among American consumers.
"We enter fiscal 2027 with momentum, a clear set of priorities and higher ambitions for what Starbucks can become," CEO Brian Niccol said in a video shared on the company’s corporate website following the earnings release.
During the company’s earnings conference call, Niccol added that Starbucks is currently running ahead of schedule to meet the ambitious fiscal 2028 targets that were initially laid out during its investor day in January. The leadership team’s forward-looking strategy appears to be focused heavily on refining the core customer experience, enhancing menu offerings, and streamlining operations both domestically and abroad.
For the upcoming fiscal year 2027, Starbucks is projecting adjusted earnings per share to land in a range of $3.15 to $3.25. This forecasted range sits comfortably above Wall Street’s consensus expectations, which had pegged earnings per share at $3.14. However, the company’s anticipated revenue trajectory presented a more cautious picture for investors. Starbucks is projecting an anticipated revenue decline of 1% for fiscal 2027, a figure that is notably weaker than expected, given that professional market analysts were previously forecasting net sales growth of 1.4%.
Despite the projected dip in overall net revenue, the company remains optimistic about specific regional metrics, projecting North American same-store sales growth of 4% for the full fiscal year.
According to CFO Cathy Smith, the company’s earnings and revenue outlook incorporates several structural factors, including an additional operational week and the financial effects of transitioning its historically massive China business to a joint venture business model. Additionally, Smith noted that Starbucks is projecting slight deflation in global coffee prices alongside slowing net new North American café openings. Both of these economic and operational factors are expected to weigh on the company’s full-year revenue generation moving forward.
Looking back at the specific financial metrics for the quarter ended September 27, Starbucks reported fiscal fourth-quarter net income attributable to the company of $677.2 million, or 59 cents per share. This represents a significant recovery compared to the same period a year earlier, when the company posted net income of $133.1 million, or 12 cents per share.
When excluding restructuring costs, impairment charges, and other one-off items, the coffee titan reported an adjusted earnings per share of 80 cents for the quarter. Meanwhile, net revenue fell 4% year-over-year to $9.14 billion, a top-line contraction that directly reflects the execution of the recent joint venture deal in China.
Despite the revenue contraction, underlying sales metrics showed considerable resilience. The company’s global same-store sales increased by 7.2%, fueled heavily by growth in the average ticket size and easily beating Wall Street estimates of 6%, according to data compiled by StreetAccount. Total transactions also grew by 1.8% during the quarter, indicating that physical foot traffic remains healthy across core markets.
Driving much of this outperformance was the domestic market. Starbucks’ U.S. cafes reported robust same-store sales growth of 7.7%, easily topping StreetAccount estimates of a 6.5% increase.
These domestic gains are largely attributed to Niccol’s signature "Back to Starbucks" turnaround strategy. Under this initiative, the company has heavily focused on dramatically improving service speeds, making its physical cafes more welcoming environments for lingering customers, and sharpening its overarching marketing campaigns. Company executives emphasized that these concerted operational changes have successfully helped to win back casual and lapsed customers alike.
"Starbucks brand affinity is at near record levels as our menu innovation, marketing and merchandise continue to create moments that drive culture and bring people into our coffee houses," Niccol told financial analysts during the call.
The success of the brand’s renewed focus on product development was prominently on display during the autumn months. The company noted that its North American rollout of its seasonal fall menu—which is anchored by the iconic pumpkin spice latte—marked the company’s strongest ever autumn launch day in its history. Furthermore, the company highlighted that matcha has officially achieved milestone status, now standing as a $1 billion drink category for Starbucks globally.
However, the international picture was notably less robust. Outside of North America, the company’s international comparable sales ticked up by just 0.9%, as ongoing traffic declines offset a modest increase in the average ticket size. That international growth rate fell noticeably short of analyst estimates, which had anticipated a 3.2% increase, according to StreetAccount.
In response to these international headwinds, Starbucks has actively restructured its global footprint. Following the transition of its massive China operations to a joint venture structure, the company has shifted the vast majority of its international business over to a licensed operational model. This shift allows local, experienced operators to take charge of day-to-day management in foreign markets. Additionally, the company has been exploring strategic alternatives for other parts of its Asian portfolio, including considering the sale of a majority stake in its Japan business, as Reuters reported in September.
From a physical footprint perspective, Starbucks opened 303 net new cafes globally during the quarter. This expansion, however, is being balanced by strategic pruning. In September, the company announced that it would close approximately 1% of its total North American footprint—amounting to roughly 250 underperforming locations—as a calculated part of its broader operational turnaround.
At the same time, the company is doubling down on the quality of its remaining real estate. By the end of the fiscal year, across the United States and Canada, Starbucks completed more than 1,700 café uplifts. These renovations are specifically designed to make stores more visually appealing and welcoming to daily customers. Company leadership has repeatedly noted that locations receiving a makeover—which often features thoughtful tweaks such as increased seating capacity and softer, more ambient lighting—consistently experience higher transaction volumes in the aftermath of the redesign.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |