
The End of the Share Buyback Era: Corporate America Shifts From Repurchasing to Issuing Equity
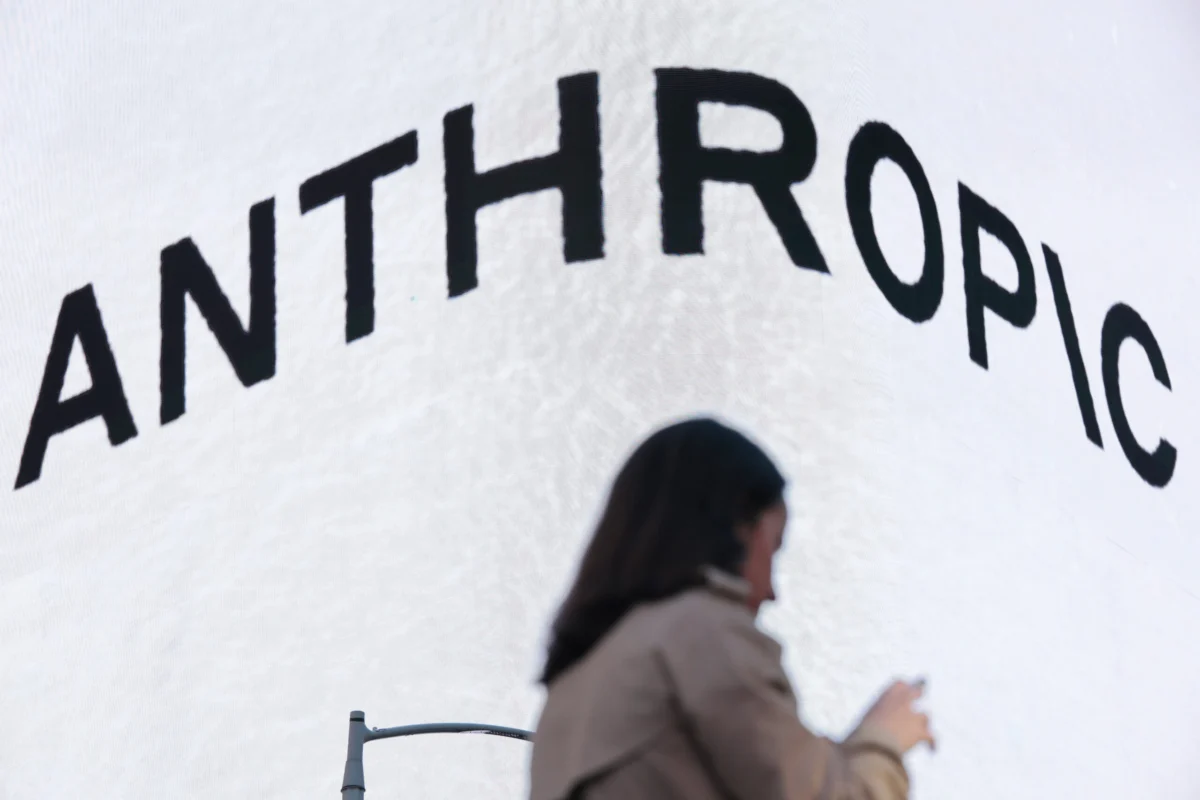
Anthropic billboards are displayed in Times Square as shares begin trading after their IPO on November 19, 2026 in New York City.
Companies have shifted decisively from buying back shares to issuing them, adding a substantial wave of new supply that the ongoing four-year-old bull market must now absorb. This structural pivot marks a profound departure from the corporate financial strategies that defined much of the post-pandemic market landscape.
"No matter how you measure it, U.S. corporations have changed their behavior over the past two years, switching from repurchasing in 2024 to issuing today," Acadian Asset Management portfolio manager Owen Lamont wrote in a letter to investors this month, pointing to a shifting tide in capital allocation. "The question you should be asking is: Why is the smart money selling?"
As of late last week, net new issuance of shares equaled 3.1% of total market capitalization, according to a recent Acadian analysis. While net issuance remains below the historical peaks witnessed during the dot-com tech bubble and the pandemic-era market boom, the analysis demonstrates that the era of aggressive corporate stock repurchases has effectively ended, giving way to an emerging era of equity issuance.
This mounting wave of supply was underscored this week by Anthropic’s blockbuster initial public offering. The offering drew intense enthusiasm initially, with the prominent frontier AI laboratory selling shares in its IPO at $83 apiece—comfortably above its expected pricing range—and ultimately raising $81 billion. However, the stock experienced downward pressure on Friday, dragging the broader stock market downward alongside it as investors digested the sheer scale of liquidity entering the financial system.
For years, many market participants have cited the steadily shrinking supply of publicly traded shares as a primary fundamental driver keeping equity prices elevated. As corporations aggressively repurchased their own stock, they systematically reduced the number of shares available for public trading, creating a powerful tailwind for prices. Simply put, there was an abundance of capital chasing a diminishing pool of shares. Furthermore, buybacks had the mechanical effect of boosting earnings per share by lowering the denominator in that critical financial ratio. Now that trend has reversed entirely, with increased equity supply acting as a potential headwind on the current bull market.
Historical research highlights the broader implications of such corporate behavior. A foundational 2000 paper by economists Malcolm Baker and Jeffrey Wurgler found that periods when companies issued more equity relative to debt were historically followed by low market returns, suggesting that corporate managers possess a keen ability to time the market when issuing securities. The Baker-Wurgler equity share index, which measures equity issuance as a share of total stock and bond issuance, peaked at approximately 18% in 2021. While it has risen in recent months, it still remains below that historic peak, as Lamont noted in his commentary.
Federal Reserve data point to a remarkably similar trend in the year-over-year changes in trailing 12-month gross stock and bond issuance. Debt gross issuance rose first in the recovery following 2020, followed closely by a wave of equity issuance in 2021. More recently, corporate debt issuance began climbing again in 2024, which was subsequently followed by a massive surge in equity issuance throughout 2026.
Recent corporate transactions vividly illustrate how major firms are tapping equity markets in diverse ways to fund their ambitious corporate strategies. Oracle filed to sell $20 billion in stock through an at-the-market program and issued another $10 billion in common shares in November. In October, Meta priced a $25 billion common-stock offering alongside $12.5 billion in mandatory convertible preferred shares. Alphabet announced a staggering $84.8 billion equity raise back in June specifically designed to help fund its massive artificial intelligence infrastructure buildout. Meanwhile, SpaceX successfully raised $85.7 billion in its June IPO after underwriters exercised their overallotment options in full.
"Before 2026, firms were net repurchasers of equity, consistent with the idea that they viewed their shares as undervalued. Today, for whatever reason, firms are issuing equity on net," Lamont wrote.
Reflecting on the broader macroeconomic and market implications of this unprecedented capital-raising cycle, the investor acknowledged that he cannot rule out the possibility that the broader financial markets are currently operating within an artificial intelligence bubble.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |