
Why the ‘Sister’ Caregiving Sketch Is Resonating Deeply Across America
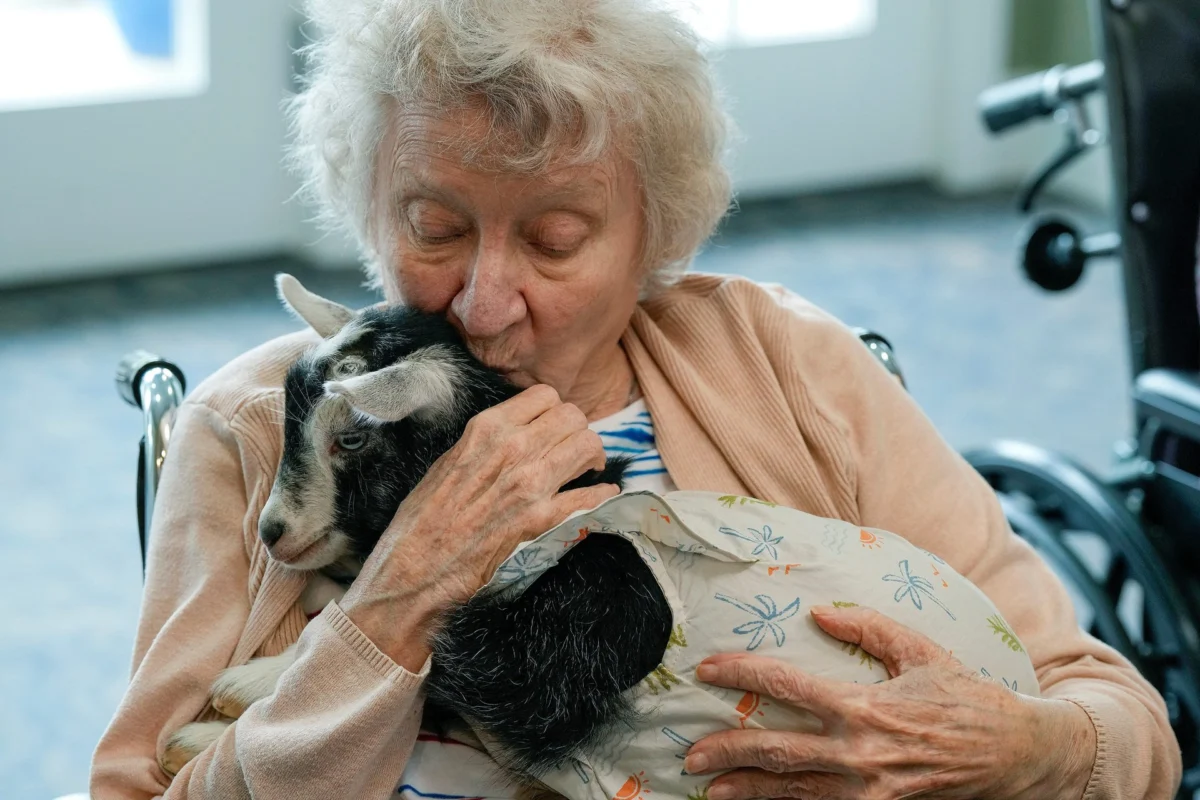
For millions of Americans, a recent Saturday Night Live sketch struck a nerve so raw they hardly knew whether to laugh or cry. The satirical bit captured the crushing, often invisible burdens that millions of women face daily when juggling the complex responsibilities of caring for aging parents.
The sketch, simply titled "Sister," targets a dynamic painfully familiar to many households: the implicit expectation that families—and brothers, in particular—will automatically relegate parental caregiving duties to their sisters. In the scenario, a brief text message reporting that a parent has suffered a fall is enough to cause a sister to instantly drop her personal and professional life to provide free, round-the-clock live-in care. As one brother character casually explains in the sketch, internalized sexism warps the sister’s brain into mistakenly believing that caretaking is exclusively her responsibility and somehow exempts the rest of the family.
The sketch quickly amassed millions of views across digital platforms overnight, a viral surge that health experts and advocates say underscores a profound, often uncomfortable societal truth. According to comprehensive data from a report by AARP and the National Alliance for Caregiving, three out of every five family caregivers are women. Many of these women find themselves caught in the grueling "sandwich generation," simultaneously responsible for the daily care of an aging parent while also raising young children. The mounting pressures have forced women to leave the workforce in staggering numbers, according to data from the human resources firm Challenger, Gray and Christmas, ultimately jeopardizing their own immediate finances and long-term retirement security.
Matthew Bourque, Managing Partner at RMO Lawyers, a firm specializing in private wealth, trust, estate, and probate disputes, notes that this dynamic almost always begins with the best of intentions. It frequently starts with a sister stepping up out of love and obligation to look after an aging father or mother. However, Bourque explains, the situation often spirals downward across a variety of scenarios as the sheer physical and emotional weight of the undertaking sets in, causing good will to fade and deep-seated familial resentment to take over.
The Hidden Cost of Caregiving Losses
While the vast majority of women report that helping a parent with essential daily tasks ultimately strengthened their personal relationship with their mother or father, the toll exacted on their own well-being is severe. According to a comprehensive Pew Research survey conducted among 8,750 U.S. adults, 38% of women stated that caregiving took a measurable toll on their physical health. Even more striking, nearly half—47%—reported a negative emotional toll. Both figures vastly exceeded those reported by men, among whom only 26% cited physical impacts and 30% reported emotional strain.
The financial fallout is equally stark. A survey of 507 adults conducted by medical alert company Bay Alarm Medical revealed that a quarter of women caring for aging parents lose $15,000 or more in annual income. By comparison, just over one in six men, or 17%, reported similar financial losses.
Over a lifetime, the economic penalty is staggering. An analysis by the Department of Labor found that unpaid care provided by women for children or adults averages a lifetime value of $295,000, adjusted for inflation based on 2021 dollar values. This unpaid family caregiving reduces a woman’s lifetime earnings by an average of 15% and severely diminishes her future retirement income.
When professional care is required during standard working hours—or when it proves simply too expensive or inaccessible—it is almost invariably mothers and daughters who scale back their paid employment to bridge the gap, noted Women’s Bureau Director Wendy Chun-Hoon when the Department of Labor study was originally released. The absence of a robust care infrastructure and safety net creates repercussions that ripple far beyond those immediate moments of crisis, impacting women throughout the entirety of their lives.
In addition to lost wages, caregivers frequently shoulder significant out-of-pocket expenses. Research from a MetLife study cited by the nonprofit Family Caregiver Alliance indicated that nearly a quarter of non-working female caregivers, and one in five working female caregivers, provided direct financial assistance to the very parents they were looking after.
How Families Can Support Caregiving Relatives
Industry experts emphasize that the most effective intervention for a caregiving sibling often needs to happen long before the daily burden becomes a crisis.
Laura LaTourette, a financial planner at Family Wealth Management Group, points out that professional financial guidance can fundamentally alter a family’s trajectory. As a financial planner, her role involves taking care of aging clients and securing what they need for their own long-term care and professional caretakers, allowing the rest of the family to simply remain a family. Financial planners do more than manage investments; they help clients map out a sustainable financial future and coordinate the complex logistics that follow.
When a family lacks a dedicated long-term care insurance policy, an experienced financial adviser can identify available community and financial resources, determine the optimal order of asset utilization, and evaluate which medical expenses may qualify for tax deductions.
Families may also explore options such as a reverse mortgage to generate the liquidity needed to pay for professional care or to finance vital home modifications—such as ramps or bathroom redesigns—that prevent dangerous falls, according to Kristen Sieffert, president of Finance of America, a home equity-based retirement financing firm. She suggests that the family home can serve as a crucial financial resource alongside Social Security and traditional retirement savings to alleviate the pressure placed on the primary family caregiver.
A reverse mortgage is a specialized loan tailored for homeowners aged 62 and older, enabling them to convert a portion of their home equity into lump-sum cash payments, a monthly income stream, a line of credit, or a combination of these options. Because the disbursed funds are generally not classified as taxable income, they typically do not interfere with Social Security or Medicare benefits. The loan itself is usually repaid only when the borrower permanently vacates the property, sells the home, or passes away.
Beyond financial instruments, early and transparent family discussions regarding individual wishes and logistical strategies are essential. Lina Supnet-Zapata, chief executive of Mir Care Consultants, a firm dedicated to helping families plan caregiving arrangements, warns that avoiding these conversations can shatter family dynamics for generations. When siblings fail to communicate about these critical matters, the friction can easily cascade down to cousins and other relatives, permanently fracturing family relationships.
These discussions should never be treated as a one-time event, according to Kerry Sette, vice president of consumer insights and research at Voya Financial. Aging parents often cannot predict years in advance which specific child will ultimately shoulder the heavier burden of caregiving, exactly how much time that care will demand, or what the financial fallout will look like. Having open dialogues early and continuously revisiting the family’s financial and caregiving blueprints can prevent damaging surprises down the road.
Legal preparation is another critical safeguard before any individual officially steps into the role of primary caregiver. Patrick Simasko, an elder law attorney and financial adviser at Simasko Law, advises that potential caregivers should consult with an elder law professional to establish proper legal standing, secure a power of attorney, and draft signed caregiver documents before undertaking physical care responsibilities. Obtaining formal legal guidance ensures that the caregiver remains protected and compliant with relevant regulations.
Furthermore, a properly structured caregiver agreement enables an aging parent to financially compensate their caregiving child directly, helping to prevent the caregiver from completely depleting their personal savings.
Experts caution, however, against informal financial arrangements. Utilizing a parent’s funds without explicit legal permission or altering legal documents such as wills and trusts outside proper channels can expose a caregiver to serious accusations of elder abuse or undue influence. Matthew Bourque notes that following the death of a parent, aggrieved siblings frequently accuse family caregivers of misappropriating their inheritance and are increasingly willing to litigate if the caregiver lacked the appropriate legal authority. The American Bar Association predicts that courts nationwide will face a surge of contested inheritance disputes in what many are calling an impending "probate storm."
Ultimately, experts return to a fundamental piece of advice for the family member who invariably takes on the heaviest load: learn to ask for help. Many women are conditioned to shoulder burdens independently, but breaking that cycle is vital to surviving the immense challenges of modern family caregiving.
| Source | : | Finance Poetry |
| Author | : | rifanmuazin |
| Editor | : | Finance Poetry Editorial Team |